July 2026 Monetary Policy Report: Full Text
Summary
Inflation has risen this year and remains elevated relative to the Federal Open Market Committee's (FOMC) longer-run objective of 2 percent, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The labor market has been broadly stable, with the unemployment rate changing little and remaining at a low level. Labor productivity growth is strong. Meanwhile, real gross domestic product (GDP) grew at a moderate pace in the first quarter, with capital investment rising considerably but household consumption increasing only very modestly. Overall, economic activity is expanding at a solid pace despite elevated uncertainty that owes, in part, to the conflict in the Middle East.
Against this backdrop and in support of the Federal Reserve's dual mandate, the FOMC has maintained the target range for the federal funds rate at 3-1/2 to 3-3/4 percent since the beginning of the year. At the June FOMC meeting, the Committee emphasized its commitment to delivering price stability.
Regarding the Federal Reserve's balance sheet, at the December 2025 meeting, the FOMC judged that reserve balances had declined to ample reserve levels and initiated the purchases of shorter-term Treasury securities as needed to maintain an ample supply of reserves on an ongoing basis. At the June meeting, the Committee reaffirmed its policy of maintaining ample reserves in the banking system.
Over the remainder of the year, independent task forces led by the very best minds from inside and outside of the economics profession, supported by key subject-matter professionals within the Federal Reserve, will examine five areas that are central to the Federal Reserve's conduct of monetary policy: (1) communications, (2) balance sheet policy, (3) the quality of existing data sources, (4) productivity and jobs in an era of transformation, and (5) frameworks for analyzing the drivers of inflation. Each task force will start with first principles, ask hard questions, examine current practice, consider alternatives, and, ultimately, propose next steps for the Federal Reserve's consideration.
Recent Economic and Financial Developments
Inflation. Inflation. Measures of consumer price changes began trending up last year and then stepped up further this spring. Over the 12 months ending in May, the price index for total personal consumption expenditures (PCE) rose 4.1 percent. Core PCE prices—which exclude often-volatile food and energy prices and are generally considered a better guide to future inflation developments—rose 3.4 percent. Both measures were notably above their year-earlier readings. Among the factors contributing to higher measured prices are earlier tariff hikes that pushed up domestic prices of some imported goods, a surge in energy prices associated with constraints on oil supplies following the start of the Middle East conflict in late February, and increased demand for some high-tech products that support artificial intelligence (AI) applications. Some measures of shorter-term inflation expectations moved higher following the jump in energy prices earlier this year. By contrast, most measures of longer-term inflation expectations have remained within the range of values observed over the decade before the pandemic and continue to be broadly consistent with the FOMC's longer-run objective of 2 percent inflation.
The labor market. The labor market. Following a period of cooling, the labor market has stabilized, with demand and supply roughly in balance. The unemployment rate, at 4.2 percent in June, was low and has been little changed since last summer. Layoffs have been subdued and job vacancies have been roughly flat, on balance, this year, though private payroll gains have picked up. A marked slowdown in immigration and ongoing declines in labor force participation due to the aging of the population led to a slowdown in labor supply growth. Finally, solid nominal wage growth has been accompanied by strong growth in labor productivity.
Economic activity. Economic activity. In the first quarter, real GDP moved up at a moderate annual rate of 2.1 percent, similar to last year's pace. The gains in the first quarter were supported by robust growth in high-tech business investment and a bounceback in federal purchases following the government shutdown in the fourth quarter of last year. Through the first five months of this year, household consumption rose at a modest average annualized rate of 1.3 percent. Activity in the housing market has remained stagnant, with both sales of existing homes and construction of new single-family homes little changed so far this year. In the manufacturing sector, output has moved up strongly this year, partly reflecting increased demand for goods related to the buildout of data centers supporting AI services. The economy's productive capacity appears to be rising at a solid pace as historically subdued growth in the labor force has been offset by strong growth in labor productivity.
Financial conditions. Financial conditions. Since the start of the year, Treasury yields have risen and the market-implied expected path of the federal funds rate has moved up. The largest increases in Treasury yields occurred at shorter maturities, as market expectations of a higher federal funds rate path pushed up real interest rates. This revised assessment by market participants of expected monetary policy appeared to reflect both the effects of the Middle East conflict on inflation and increased confidence in the stability of the labor market. Broad equity price indexes moved up, while yields on corporate bonds rose moderately. Credit remained broadly available to most nonfinancial firms, households, and municipalities, although small businesses and households continued to face relatively tight credit conditions. Bank lending grew in the first half of 2026, likely reflecting easier lending standards and stronger demand.
In the modern economy, it is difficult to measure the stock of money. One of a number of series traditionally used to provide an empirical approximation to the stock of money is the M2 monetary aggregate. Over the first five months of the year, 12-month rates of increase in M2 were moderate and broadly similar to the pace typically observed during the 2010s.
Financial stability. Financial stability. Overall, the U.S. financial system remained sound and resilient, with vulnerabilities roughly unchanged, on net, since the beginning of the year. Asset valuations remain above historical norms across equity, corporate debt, and residential real estate markets. Total debt of nonfinancial businesses and households as a fraction of GDP continued to edge down over the first half of 2026 and currently stands at its lowest level since the early 2000s. Leverage of hedge funds and the largest life insurers remained elevated relative to historical standards. Risk-based regulatory capital levels at banks stayed high compared with the past few decades, and bank capital positions became less sensitive to increases in long-term yields. Assessments of vulnerabilities stemming from funding risks are consistent with historical norms across most sectors of the financial system. Some private credit vehicles faced notable increases in redemption requests in the first quarter of 2026, reflecting some defaults and concerns about the quality of underlying assets. In most cases, the managers of these funds imposed limits on redemptions, and private credit markets continued to function normally. (See the box "Developments Related to Financial Stability.")
International developments. International developments. Growth in foreign economic activity was subdued overall in the first half of 2026, in part reflecting headwinds generated by the Middle East conflict and U.S. tariffs. However, these headwinds were partially offset by the surge in AI-related investment. Foreign headline inflation has increased notably in recent months in response to the sharp rise in prices of energy and other related commodities during the conflict. Foreign producer prices have also risen, possibly posing additional inflationary risks abroad. In response, several foreign central banks raised their policy rates, and others shifted their communications to emphasize their commitment to price stability, despite weaker growth prospects. Equity prices abroad rose even as foreign sovereign bond yields increased. The trade-weighted exchange value of the U.S. dollar has appreciated modestly, on net, since the start of this year, remaining strong in real terms relative to its historical average.
Monetary Policy
Interest rate policy. Interest rate policy. In support of the Federal Reserve's dual mandate, the FOMC has maintained the target range for the federal funds rate at 3-1/2 to 3-3/4 percent since the beginning of the year. The Committee has noted that economic activity is expanding at a solid pace despite elevated uncertainty that owes, in part, to the conflict in the Middle East; productivity growth and capital investment are strong; job gains have kept pace with the workforce; and the unemployment rate has changed little. Inflation remains elevated relative to the Committee's 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability.
Balance sheet policy. Balance sheet policy. At the December 2025 meeting, the FOMC judged that reserve balances had declined to ample reserve levels and initiated purchases of shorter-term Treasury securities to maintain an ample supply of reserves on an ongoing basis. At the June meeting, the Committee reaffirmed its policy of maintaining ample reserves in the banking system.
Special Topics
Employment and earnings across groups. Employment and earnings across groups. Employment disparities across sex, race, ethnicity, and education continue to be relatively narrow compared with historical levels. Nevertheless, significant disparities in absolute levels remain. Additionally, the robust real wage gains experienced by some historically disadvantaged groups in recent years have since moderated as labor market tightness has eased and consumer price inflation has remained elevated. (See the box "Employment and Earnings across Demographic Groups.")
Federal Reserve's balance sheet and money markets. Federal Reserve's balance sheet and money markets. The FOMC continued reserve management purchases to maintain an ample supply of reserves. Usage of the overnight reverse repurchase agreement facility remained near zero on most days, and standing repurchase agreement operations were tapped when economically sensible. Overnight money markets were stable. (See the box "Developments in the Federal Reserve's Balance Sheet and Money Markets.")
Monetary policy rules. Monetary policy rules. Policymakers routinely consult information derived from the analysis of simple monetary policy rules. However, existing rules cannot capture all of the considerations that go into the formation of appropriate monetary policy; nevertheless, some principles of effective monetary policy can be understood by examining the current policy implications of these rules. (See the box "Monetary Policy Rules in the Current Environment.")
Domestic Developments
Inflation trended up last year and moved notably higher in recent months
After having fluctuated around a rate somewhat above the Federal Open Market Committee's (FOMC) 2 percent target in 2024 and early 2025, measures of consumer price inflation moved up steadily over the remainder of last year amid signs that increases in tariffs on U.S. goods imports had pushed up domestic prices for some consumer goods. Measured inflation then stepped up further in March as energy prices surged after the start of the Middle East conflict. Over the 12 months ending in May, the price index for personal consumption expenditures (PCE) rose 4.1 percent, up substantially from a 2.5 percent pace a year earlier (figure 1). Core price inflation—which excludes food and energy items and historically has been a better gauge of future inflation—was 3.4 percent over the 12 months ending in May, up from a 2.8 percent pace a year earlier. By contrast, some other measures of inflation that attempt to reduce the influence of idiosyncratic price movements have moved lower over the past year. For example, the 12-month change in the trimmed mean measure of PCE prices constructed by the Federal Reserve Bank of Dallas declined from 2.6 percent last May to 2.4 percent this May.2
Personal consumption expenditures price indexes
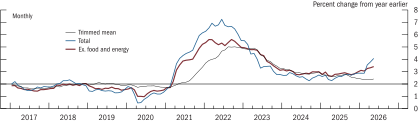
The horizontal line indicates the Federal Open Market Committee's objective of 2 percent inflation.
Source: For trimmed mean, Federal Reserve Bank of Dallas; for all else, Bureau of Economic Analysis; all via Haver Analytics.
Consumer energy prices have risen sharply since February, while food prices continued to increase moderately
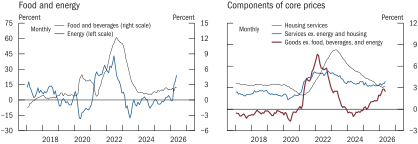
PCE energy prices leaped 24 percent over the 12 months ending in May (figure 2, left panel). Much of the gain reflects a jump in oil and gasoline prices following the start of the military conflict in the Middle East, which severely constrained shipping through the Strait of Hormuz—a key passageway for oil—and damaged some of the region's energy infrastructure. As a consequence, oil prices rose sharply and have been volatile since then, fluctuating on news regarding negotiations between the U.S. and Iran (figure 3).
Price indexes for subcomponents of personal consumption expenditures
Percent change is from year earlier.
Source: Bureau of Economic Analysis via Haver Analytics.
Oil prices
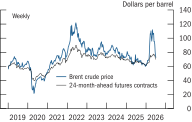
The data are weekly averages of daily data and extend through July 2, 2026.
Source: ICE Brent Futures via Bloomberg.
Series: Brent crude price and 24-month-ahead futures contracts Horizon: January 4, 2019, to July 2, 2026 Description: A line chart with two curves over January 4, 2019, to July 2, 2026. Units are dollars per barrel. The data are weekly averages of daily data. The Brent crude price series starts a bit below 60 and fluctuates between about 60 and 75 through 2019 until it falls sharply to nearly 20 by mid-2020. The series climbs steadily to and peaks at about 120 in mid-2022 and then slides gradually to about 60 by the start of 2026, with intermediate peaks a bit above and below 90 in September 2023 and April 2024, respectively. The series recovers to about 70 by February 2026 and then soars up to about 110 by the end of March 2026. It fluctuates between about 90 and 110 through mid-June before plunging to and ending at about 75. The 24-month-ahead futures contracts series, while a bit less volatile in its movements, largely follows the Brent crude price series. The series starts at around 60 and hovers between about 55 and 65 in 2019. It drops to about 40 by mid-2020 before rising steadily to about 90 in mid-2022 and then receding to about 60 by the start of 2026. It jumps more modestly in March 2026, to about 75, and fluctuates between about 75 and 80 before dropping abruptly to and finishing at about 70.
Although the pace of increase in PCE food prices remained moderate, it has picked up this year. Food prices rose 2.4 percent over the 12 months ending in May, up from 1.8 percent at the same time last year (figure 2, left panel). A few somewhat interrelated factors contributing to the step-up in measured food price inflation include the effects of higher tariffs and increases in agricultural and livestock commodity prices (figure 4, blue line).
Spot prices for commodities
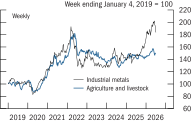
The data are weekly averages of daily data and extend through July 2, 2026.
Source: For industrial metals, S&P GSCI Industrial Metals Spot Index; for agriculture and livestock, S&P GSCI Agriculture & Livestock Spot Index; both via Haver Analytics.
Lower-income households are particularly sensitive to changes in the costs of food and energy, as these necessities account for a large share of their expenditures. Reflecting the sharp run-ups seen in 2021 and 2022, as well as the increase this year, food prices are almost 30 percent higher than before the pandemic, well above the 8 percent increase that would have been observed if these prices had continued rising at their average rates over the decade before the pandemic.3
Core goods price inflation continued to move up early this year
In assessing the outlook for inflation, it is helpful to consider three separate components of core prices: core goods, housing services, and core nonhousing services (figure 2, right panel). Core goods price inflation moved up notably over 2025 and continued to rise in the early months of this year. The 12-month change in PCE core goods prices stood at 2.4 percent in May, far higher than the 0.6 percent pace recorded a year earlier.
The effects of tariffs cannot be observed directly in the official consumer price statistics, and these effects depend on the responses of consumers, firms, importers, and foreign exporters. Nonetheless, the pattern of price changes last year suggests that tariff increases contributed in part to the upturn in consumer goods price increases. As an example, relative to their pre-tariff trends, average monthly price increases were higher in goods categories that are more exposed to tariff increases due to their relatively high import content, such as household appliances and a variety of consumer electronics.
In the early months of 2026, rapid gains in consumer prices for software and accessories, computers, and other electronics also contributed to overall measured core goods inflation.4 These prices are quite elevated relative to their year-earlier levels, and the gains likely reflect the surge in demand for semiconductors and other components important to the buildout of data centers that provide the infrastructure needed for artificial intelligence (AI) applications and services. Although a large portion of high-tech goods are imported, most of these products are exempt from tariffs, so changes in tariff rates are not an important factor in their prices.
Rising prices for fuel, metals, and other key inputs have increased cost pressures on domestic manufacturers and are likely feeding into core goods prices. This year, purchasing managers have reported in both the Institute for Supply Management manufacturing survey and regional Federal Reserve surveys that the prices they paid for inputs used in production moved higher (figure 5). Many respondents cited geopolitical tensions in the Middle East, rising fuel and transportation costs, and broad supply constraints as primary drivers of these elevated input costs. Indeed, global benchmark prices for industrial metals have risen considerably, on net, this year, likely reflecting supply constraints resulting from the conflict in the Middle East and increased demand arising from data center construction and outfitting (figure 4, black line). Finally, the Federal Reserve Bank of New York's Global Supply Chain Pressure Index—which incorporates information from a range of sources—indicates that supply chain pressures have jumped in recent months.
Prices paid indexes from manufacturing surveys
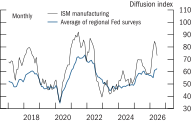
The data extend through June 2026. The regional survey average comprises data from the Dallas Fed's Texas Manufacturing Outlook Survey, the Kansas City Fed's Survey of Tenth District Manufacturers, the New York Fed's Empire State Manufacturing Survey, and the Philadelphia Fed's Manufacturing Business Outlook Survey. ISM is Institute for Supply Management.
Source: Institute for Supply Management, Manufacturing Report on Business; Federal Reserve Bank of Dallas, Texas Manufacturing Outlook Survey; Federal Reserve Bank of Kansas City, Survey of Tenth District Manufacturers; Federal Reserve Bank of New York, Empire State Manufacturing Survey; Federal Reserve Bank of Philadelphia, Manufacturing Business Outlook Survey; all via Haver Analytics.
Published nonfuel import prices, which measure the prices charged by foreign suppliers and exclude tariffs, have risen sharply this year, driven up by higher prices for industrial metals, computers, and semiconductors (figure 6). By contrast, the prices paid by domestic producers to import these products, which do include tariffs, are estimated to have decreased this year. These price reductions primarily reflect a decline in the average U.S. tariff rate following February's Supreme Court ruling that invalidated many prevailing tariff measures and whose repeal was only partially offset by new, alternative tariff measures.
Nonfuel import price index
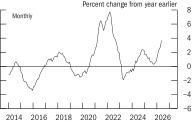
The missing value for the nonfuel import price index in October 2025 is estimated using the average of the September 2025 and November 2025 values.
Source: Bureau of Labor Statistics.
Housing services price inflation moved lower
Housing services price inflation declined considerably last year and is now close to its pre-pandemic pace. Over the 12 months ending in May, housing services prices rose 3.2 percent, a notably smaller gain than the 4.1 percent increase for the comparable period in 2025 (figure 7).
Measures of rental price inflation
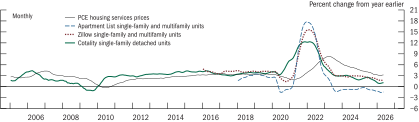
The data start in January 2016 for Zillow and January 2018 for Apartment List. PCE is personal consumption expenditures. Apartment List, Zillow, and Cotality data measure market-rate rents—that is, rents for a new lease by a new tenant.
Source: Bureau of Economic Analysis, PCE, via Haver Analytics; Apartment List, Inc., via Haver Analytics; Zillow, Inc.; Cotality; Federal Reserve Board staff calculations.
Core nonhousing services price inflation remains above its pre-pandemic average
Finally, prices for core nonhousing services—a broad group that includes medical, travel and dining, and financial services—increased 3.9 percent over the 12 months ending in May, somewhat above the range of readings this measure has recorded since the middle of last year. Robust increases in prices for medical services, accommodations, and airfares (likely due to a recent surge in jet fuel prices) have contributed to the gains in this category. Despite the recent uptick in the pace of price increases, there do not appear to be persistent cost pressures for firms in this sector, where labor is the most important input: Wage growth has declined gradually in recent years, and even though it remains at a solid level, it has been accompanied by strong productivity growth.
Most measures of longer-term inflation expectations have been stable, while most measures of shorter-term expectations have risen in recent months
A generally held view among economists is that inflation expectations influence actual inflation by affecting wage- and price-setting decisions. Most measures suggest that longer-term inflation expectations remain well anchored. Survey-based measures produced by Blue Chip Financial Forecasts, the Federal Reserve Banks of New York and Atlanta, and the Survey of Professional Forecasters from the Federal Reserve Bank of Philadelphia have moved roughly sideways in recent months and remain within the range seen in the decade before the pandemic, when inflation was low (figure 8).5 For example, the median forecaster in the Survey of Professional Forecasters continued to expect inflation to average 2.1 percent over the five years beginning five years from now. Similarly, market-based measures of longer-term inflation compensation based on financial instruments linked to inflation have been little changed so far this year (figure 9).
Measures of inflation expectations
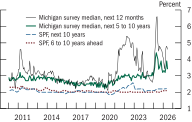
The data for the Michigan survey are monthly and extend through June 2026. The data for the Survey of Professional Forecasters (SPF) are quarterly and extend through 2026:Q2.
Source: University of Michigan Surveys of Consumers; Federal Reserve Bank of Philadelphia, SPF.
Inflation compensation implied by Treasury Inflation-Protected Securities
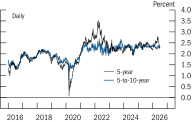
The data are at a business-day frequency and are estimated from smoothed nominal and inflation-indexed Treasury yield curves.
Source: Federal Reserve Bank of New York; Federal Reserve Board staff calculations.
Series: 5-to-10-year and 5-year Horizon: January 4, 2016, to July 2, 2026 Description: A line chart with two curves over January 4, 2016, to July 2, 2026. Units are percent, and the data are daily. The 5-to-10-year series begins around 1.7 in January 2016. It then steps down gradually to a bit below 1.5 in June 2016, rises to 2 in January 2017, and drops again to 1.8 in June 2017. The series then grows to about 2 in January 2018, moderates to about 1.5 by the end of February 2020, and then falls below 1 in March 2020 before returning to about 1.5 in April 2020. The series steadily climbs to about 2.5 by May 2021 and fluctuates between approximately 2 and 2.5 through mid-April 2022 before briefly hitting close to 2.8 in late April. The series then drops to just above 2 in late May 2022 and fluctuates between just below 2 and about 2.5 through May 2023 before increasing to above 2.5 in September 2023 and remaining there through November 2023. It then dips to about 2.1 in December 2023, climbs to around 2.4 by February 2024, and fluctuates between 2.2 and 2.5 until August, when it dips to between 2.1 and 2.2 until October 2024. The series swings up to nearly 2.5 in early November and then ticks down, fluctuating around 2.3 through December 2024. At the beginning of 2025, the series edges up and fluctuates between around 2.4 and 2.5 through February 2025 before falling to about 2.3 and hovering between 2.2 and 2.3 through the beginning of May 2025. The series then increases to around 2.4 and fluctuates near that level through July 2025 before dipping to just above 2.3 at the beginning of August 2025. From August 2025 through February 2026, it hovers between about 2.3 and 2.4. The series then dips to just below 2.3 in March and continues to hover between around 2.2 and 2.3 until mid-May, when it climbs back up to just under 2.4. It then hovers between about 2.3 and 2.4 through the end of June, briefly dipping below 2.3 before ending just above 2.3. From early 2016 through February 2020, both series are nearly identical. The 5-year series subsequently falls to just above 0 by mid-March 2020 before jumping to over 2.7 in May 2021, surpassing the 5-to-10-year series. From there, the series fluctuates slightly, ramping up to more than 3 in November 2021, retreating slightly to about 2.8 by December 2021, and remaining around there through most of February 2022. In late February 2022, the series begins to rise, peaking around 3.5 in late March 2022. It drops briefly to below 3.3 in early April before increasing again to nearly 3.5 in late April 2022. From there, the series decreases to just below 3 in mid-May and remains roughly between 2.8 and just above 3 through mid-June 2022. The series then falls to slightly above 2 by the end of September 2022 before rebounding to over 2.5 in late October 2022. The series then follows the 5-to-10-year series closely until early March 2023, when it rises to nearly 2.8. Over the next three months, the series declines slowly past the 5-to-10-year series to just above 2 by mid-June 2023. The series increases and peaks around 2.4 by mid-October 2023. It fluctuates between just above 2 and nearly 2.5 until late July 2024, when it falls to around 2. The series rises to around 2.3 in October 2024 and crests around 2.4 in early November. It then fluctuates around 2.3 for the rest of 2024 before hovering just below 2.5 in January 2025. The series then inches up to and fluctuates around 2.5 in February 2025. The series decreases to and hovers between around 2.4 and 2.5 through March, declines to about 2.2 in mid-April 2025, and steadily increases to and fluctuates around 2.4 through early July before rising to and hovering around 2.5 through the end of July 2025. The series decreases to about 2.4 at the beginning of August, hovers between around 2.4 and 2.5 through mid-August, and then climbs up to above 2.5 through the beginning of September 2025. The series remains relatively stable between about 2.4 and 2.5 through mid-October before dipping to around 2.3, where it stays until late November 2025. From November through the end of 2025, it trends downward, declining to just below 2.2. The series then rebounds in January 2026, rising steadily to about 2.5 by month-end before easing back and fluctuating between around 2.3 and 2.4 through February. It strengthens again in March, climbing above 2.6 by mid-month, and hovers between about 2.5 and 2.6 through mid-April. By the end of April, it rises above 2.7 and continues to fluctuate between about 2.6 and 2.8 through May. The series then trends downward, ending around 2.3 in early July.
By contrast, most measures of shorter-term inflation expectations have risen this year—particularly since the start of the conflict in the Middle East—though the extent of the increases has varied considerably. At one extreme, 12-month inflation expectations in the University of Michigan survey rose from 3.4 percent in February to 4.6 percent in June, an elevated rate that was nevertheless still well below the peak that followed last year's announcements of tariff increases (figure 8, black line). Other short-term measures, such as those produced by the Federal Reserve Bank of New York's Survey of Consumer Expectations, the Blue Chip survey, and many measures of businesses' expectations of inflation and cost increases, have risen less dramatically or have changed little, on net, as have market-based inflation compensation measures.
A task force will explore inflation frameworks
Against the backdrop of persistently elevated inflation, the Federal Reserve has commissioned an independent task force to explore inflation frameworks. In particular, the task force will examine the drivers of inflation, consider first principles, and weigh a wide range of ideas on how monetary policy can deliver price stability in a changing economy.
Labor market conditions have been broadly stable so far this year
As measured across a range of indicators, the labor market has stabilized this year following a period of cooling. In June, the unemployment rate stood at 4.2 percent—low by historical standards—and it has been little changed this year (figure 10). Similarly, unemployment rates across most demographic groups have held stable at low levels (figure 11). (The box "Employment and Earnings across Demographic Groups" provides further details.) Layoffs have been subdued, and job vacancies have been roughly flat on net. Meanwhile, job growth has picked up so far this year, although it remains soft by historical standards: Following very anemic average monthly gains of about 30,000 in the second half of last year, private payroll gains increased to nearly 80,000 in the first quarter of this year and then stepped up further to almost 100,000 in the second quarter (figure 12). Across industries, while employment growth in health care has been relatively strong, other industries have posted more modest gains, with employment in leisure and hospitality, information, and financial activities recording declines.
Civilian unemployment rate
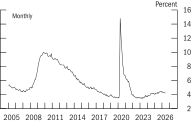
The data extend through June 2026. Missing data for October 2025 are estimated using the average of the September 2025 and November 2025 values.
Source: Bureau of Labor Statistics via Haver Analytics.
Unemployment rate, by race and ethnicity
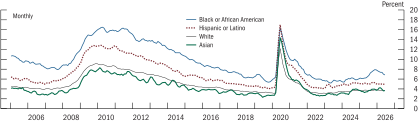
All data shown are 3-month moving averages and extend through June 2026. Unemployment rate measures total unemployed as a percentage of the labor force. Persons whose ethnicity is identified as Hispanic or Latino may be of any race. Small sample sizes preclude reliable estimates for Native Americans and other groups for which monthly data are not reported by the Bureau of Labor Statistics. Missing data for October 2025 are estimated using the average of the September 2025 and November 2025 values.
Source: Bureau of Labor Statistics via Haver Analytics.
Nonfarm payroll employment
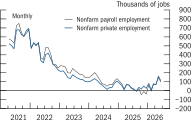
The data shown extend through June 2026 and are a 3-month moving average of the change in nonfarm payroll employment.
Source: Bureau of Labor Statistics via Haver Analytics.
Growth in labor supply has been historically low...
Growth in the supply of labor—determined by both the growth of the working-age population and changes in the labor force participation rate, which is the share of the population either currently employed or actively looking for work—has slowed notably over the past two years to a pace that is extremely subdued relative to historical norms.6 Much of the slowdown can be attributed to a sharp reduction in net immigration. According to estimates produced by the Census Bureau, strong immigration from 2022 through 2024 contributed to elevated population growth in those years, but immigration slowed markedly over the 12 months ending in June 2025; more recent indicators point to very low immigration and population growth since then. Meanwhile, the labor force participation rate has moved down since reaching its recent peak in 2023, reflecting downward pressure from population aging (figure 13).
Labor force participation rate
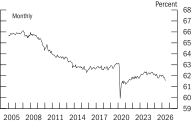
The data extend through June 2026. Values before January 2026 are estimated by Federal Reserve Board staff to eliminate discontinuities in the published history. Missing data for October 2025 are estimated using the average of the September 2025 and November 2025 values.
Source: Bureau of Labor Statistics via Haver Analytics.
. . . and growth in labor demand appears to have stabilized at a modest pace
Job openings, as measured in the Job Openings and Labor Turnover Survey (JOLTS), have moved a little higher since late last year. Meanwhile, an alternative measure of vacancies that uses job postings data produced by Indeed, a large online job board, has flattened out this year following declines in previous years. Indicators of layoff activity have remained muted, as initial claims for unemployment insurance have been moving sideways, on net, and the JOLTS layoff rate has averaged only 1.1 percent so far this year, similar to its pre-pandemic average (figure 14).
Indicators of layoffs
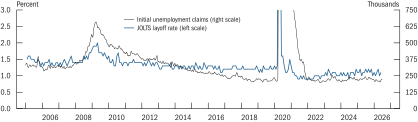
The data for initial unemployment claims cover regular state programs, are reported as a 4-week moving average, and extend through June 27, 2026. The data for the Job Openings and Labor Turnover Survey (JOLTS) layoff rate are monthly. Series are truncated at the top of the figure in 2020 and 2021.
Source: Bureau of Labor Statistics via Haver Analytics; Department of Labor, Employment and Training Administration.
With growth in labor supply and demand about equally subdued, many key indicators of labor market conditions and resource utilization have been broadly stable
Various indicators that track labor market conditions have held mostly steady this year, suggesting that the labor market has become neither notably more nor less tight. For example, the JOLTS measure of the percentage of workers quitting their jobs each month—an indicator of the availability of attractive job prospects—has been largely flat in recent months. Additionally, the gap between the total number of available jobs (measured by employed workers plus job openings) and the number of available workers (measured by the size of the labor force) has edged slightly higher this year after having drifted a bit lower last year (figure 15). Finally, after declining steadily through last year, the share of respondents to the Conference Board Consumer Confidence Survey who say that jobs are plentiful flattened out in early 2026, though it moved down in June.
Available jobs versus available workers
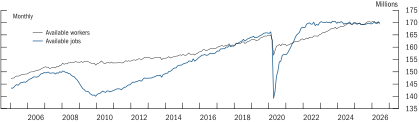
The data extend through June 2026. Available jobs are employment plus job openings as of the end of the previous month. Available workers are the labor force. Data for employment and labor force before January 2026 are estimated by Federal Reserve Board staff to eliminate discontinuities in the published history. Missing data for October 2025 are estimated using the average of the September 2025 and November 2025 values.
Source: Bureau of Labor Statistics via Haver Analytics; Federal Reserve Board staff calculations.
Labor productivity increased robustly last year
Since late 2019, business-sector labor productivity growth has averaged 2.1 percent per year—notably faster than the 1.5 percent average pace over the previous business cycle between the fourth quarters of 2007 and 2019 (figure 16). The strong gains in productivity over the past few years are likely attributable to a variety of factors, including firms' investments in labor-saving technologies and high-tech capital to improve efficiency as well as the elevated pace of business formation since 2020. More recently, businesses' adoption of AI technologies could also be a contributing factor, albeit modest to date.
Average U.S. labor productivity growth
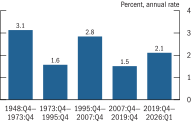
The data are output per hour in the business sector.
Source: Bureau of Labor Statistics via Haver Analytics; Federal Reserve Board staff calculations.
A task force will explore productivity and jobs
One of the recently announced independent task forces will explore the subject of productivity and jobs. It will survey the pace, the reach, and the economic effects of generative AI—a new general-purpose technology—and other innovations. The task force will explore the implications for the Federal Reserve in pursuit of its maximum-employment and price-stability mandates.
Wage growth remains solid and, with persistently strong productivity growth, is roughly consistent with 2 percent inflation over time
Measures of nominal wage growth remain solid, although they have edged down this year on net. Total hourly compensation for private-sector workers, as measured by the employment cost index, increased 3.4 percent over the year ending in March, unchanged from its pace a year earlier but well below its peak increase of 5.5 percent in mid-2022 (figure 17). However, other measures of labor compensation growth, such as average hourly earnings (a less comprehensive measure of compensation) and the Federal Reserve Bank of Atlanta's Wage Growth Tracker (which reports the median 12-month wage growth of individuals responding to the Current Population Survey), have moved lower over the past year.
Measures of change in hourly compensation
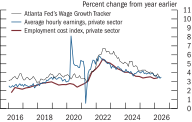
For the Atlanta Fed's Wage Growth Tracker, the data are shown as a 3-month moving average of the 12-month percent change; for private-sector average hourly earnings, the data are 12-month percent changes and extend through June 2026; for the private-sector employment cost index, change is over the 12 months ending in the last month of each quarter.
Source: Bureau of Labor Statistics; Federal Reserve Bank of Atlanta, Wage Growth Tracker; all via Haver Analytics.
Although wage growth remains a touch above its pre-pandemic pace, persistently strong labor productivity growth suggests that current nominal wage growth is roughly consistent with 2 percent inflation over time.
Solid nominal wage gains have nonetheless been outpaced by overall price inflation over the past year. With the recent jump in energy prices boosting the change in PCE prices to 4.1 percent over the 12 months ending in May, the purchasing power of workers' wages, in the aggregate, declined somewhat over this period. That said, for the year ending in May 2025, wage gains outpaced price inflation. The effects on individual households, though, depend in part on workers' circumstances—because nominal wage changes vary significantly across industry and occupation and because households consume different baskets of goods than the one represented in the aggregate PCE price index. (For details on how real wage gains have differed across demographic groups, see the box "Employment and Earnings across Demographic Groups.")
Employment and Earnings across Demographic Groups
Employment disparities across sex, race, ethnicity, and education groups—some of which reached record lows in 2023 and early 2024 in an especially tight labor market—continue to be relatively narrow compared with historical levels. However, despite the labor market progress for many demographic groups in recent years, significant disparities in absolute levels across groups remain. Additionally, the robust real wage gains experienced by some historically disadvantaged groups in recent years have since moderated as labor market tightness has eased and consumer price inflation has remained elevated.
Among prime-age people (aged 25 to 54), the employment-to-population (EPOP) ratio for Black or African American workers softened considerably in the first half of 2025 but has since partially recovered and, in recent months, has been a touch above its average level in 2019 (figure A, left panel).1 This development primarily reflects an increase in the unemployment rate for this group over early 2025 that has since partially reversed.2 At the same time, the employment rate for white workers has continued to gradually drift higher over the past year. As a result, the EPOP ratio gap between Black and white individuals has widened, on net, over the past year, although it remains narrow compared with its historical level.3 By contrast, the employment rate for Hispanic or Latino workers has held roughly steady, on net, over the past year, while the employment rate for Asian workers has edged down a touch, although the ratios for both groups are elevated by historical standards. The EPOP ratio gap between Hispanic and white workers is roughly unchanged relative to a year ago, while the gap between Asian and white workers has widened.4
Prime-age employment-to-population ratios compared with the 2019 average ratio, by group
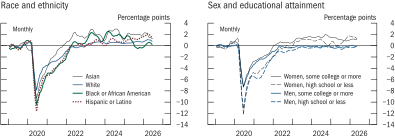
The data are 3-month moving averages. The data by race and ethnicity extend through June 2026. Prime age is 25 to 54. All series are seasonally adjusted by Federal Reserve Board staff. Data by sex and education before January 2026 are estimated by Federal Reserve Board staff to eliminate discontinuities in the published history. Missing data for October 2025 are estimated using the average of the September 2025 and November 2025 values.
Source: Bureau of Labor Statistics; U.S. Census Bureau, Current Population Survey; Federal Reserve Board staff calculations.
The EPOP ratio for prime-age women grew strongly during the post-pandemic recovery and peaked in 2024, which led to a historically narrow EPOP ratio gap between prime-age men and women. This increase in the EPOP ratio for women mostly reflects the continuation of the pre-pandemic trend of rising female labor force participation—some of which is likely attributable to increased educational attainment—among other factors.5 In the past year, growth in the female EPOP ratio has leveled off, but given that the male EPOP ratio has been roughly flat over this time, the employment gap between men and women has remained near its low point. Both women with and without some college education currently have EPOP ratios a bit above their pre-pandemic levels (figure A, right panel). By contrast, male EPOP ratios are about equal to their pre-pandemic levels for both these education groups.
Among all prime-age people (aged 25 to 54), the EPOP ratio has remained roughly stable over the past year (figure B). The EPOP ratio for people aged 55 or older, though, has continued to gradually decline and is now approximately 3.5 percentage points below its 2019 average. Most of this shortfall relative to 2019 reflects retirements related to the aging of the baby-boom generation. As this cohort has grown older, the median age of people in the aged 55 or older population has risen, and because older workers are more likely to have retired, this trend has lowered the group's EPOP ratio. Further, workers in this group, particularly those aged 65 or older, began retiring somewhat earlier than usual during the pandemic, which has put some additional downward pressure on their EPOP ratio.6 After falling a fair bit from its post-pandemic peak in 2024, the EPOP ratio of younger workers (aged 16 to 24) has remained flat, on net, over the past year, and now sits a touch below its average level in 2019. The net decline relative to 2024 likely reflects a combination of factors particular to this age group: greater sensitivity of labor force participation decisions to the easing labor market conditions of the past two years, potential vulnerability to the adoption of generative artificial intelligence (GenAI) across employers, and potential negative effects of remote-work policies on early-career workers.7
Employment-to-population ratios compared with the 2019 average ratio, by age
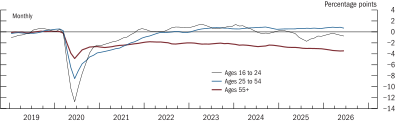
The data are 3-month moving averages and extend through June 2026. All series are seasonally adjusted by Federal Reserve Board staff. Data before January 2026 are estimated by Federal Reserve Board staff to eliminate discontinuities in the published history. Missing data for October 2025 are estimated using the average of the September 2025 and November 2025 values.
Source: Bureau of Labor Statistics; U.S. Census Bureau, Current Population Survey; Federal Reserve Board staff calculations.
Although employment disparities across many demographic groups remain near the historical lows reached during the post-pandemic recovery period, substantial gender, racial, ethnic, and geographic gaps in levels persist. Currently, prime-age women are employed at a rate 11 percentage points less than men, while prime-age Black and Hispanic workers are employed at a rate 6 percentage points and 3 percentage points below white workers, respectively, underscoring long-standing structural factors.8
Real wage growth has cooled a bit further in the past year as consumer price inflation has stepped up. Earlier in the current expansion, the tight labor market led to robust real wage growth, particularly for lower-wage workers and for many historically disadvantaged groups; however, since mid-2024, wage growth for these groups has slowed. As shown in the top-left panel of figure C, real wage growth—as measured by the Federal Reserve Bank of Atlanta's Wage Growth Tracker and deflated by the personal consumption expenditures price index—was generally stronger for workers in the bottom half of the income distribution during the post-pandemic recovery through the first half of 2024. This strength was driven by both labor demand outpacing labor supply in lower-wage industries during the post-pandemic reopening of the economy and strong wage growth for job switchers over the same period who were disproportionately lower-wage workers.9 However, since late 2024, real wage growth for workers in the bottom quartile has fallen below that of the other quartiles but has remained positive, on average, over the past 12 months. Real wage growth among the highest income quartile remained robust through mid-2025 but has since slowed sharply. (The data used in this discussion to measure real wage growth across demographic groups are a 12-month moving average and are therefore lagged relative to actual real wage growth.10 As a result, the group-specific real wage growth measures discussed here remain positive even while the aggregate real wage growth measures discussed elsewhere in this report have turned negative.)
Median real wage growth, by group
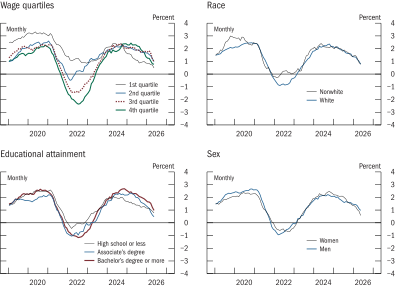
Series show 12-month moving averages of the median percent change in the hourly wage of individuals observed 12 months apart, deflated by the 12-month moving average of the 12-month percent change in the personal consumption expenditures price index. In the top-left panel, workers are assigned to wage quartiles based on the average of their wage reports in both Current Population Survey outgoing rotation group interviews; workers in the lowest 25 percent of the average wage distribution are assigned to the 1st quartile, and those in the top 25 percent are assigned to the 4th quartile.
Source: Federal Reserve Bank of Atlanta, Wage Growth Tracker; Bureau of Labor Statistics; U.S. Census Bureau, Current Population Survey; Federal Reserve Board staff calculations.
The recent cooling in real wage growth is visible across all broad demographic groups, including among some groups for whom, up until a year ago, wage growth had remained robust. Wage growth for nonwhite workers had been a bit stronger than for white workers from 2022 through mid-2024 but has been similar to white workers' since then (figure C, top-right panel). Similarly, wage growth for workers with a high school diploma or less was strong relative to other groups in the post-pandemic tight labor market; however, as labor market conditions softened in 2024, wage growth for this group fell below that for college-educated workers in early 2024 and has been slowing, on net, since mid-2024 (figure C, bottom-left panel). Some of this softening may be spreading to workers with an associate's degree, for whom real wage growth has eased more significantly in the past year and currently stands below that for other education groups. Finally, wages for men and women largely grew in tandem until the middle of 2024, but real wage growth for women was a bit stronger than that for men from mid-2024 through mid-2025 (figure C, bottom-right panel). However, in recent months, wage growth for women has tapered a bit and is now a touch below that of men.
Gross domestic product growth has been moderate
Real gross domestic product (GDP) moved up 2.1 percent at an annual rate in the first quarter of this year, about the same pace as last year (figure 18). The first-quarter gain was supported by solid growth in high-tech-related business investment and a bounceback in real federal purchases following the government shutdown in the fourth quarter of last year. However, first-quarter output growth was tempered somewhat by a decline in residential investment, by a very modest gain in consumer spending, and by the high import share of AI-related business spending, as imports are subtracted from other spending flows in the GDP calculation to isolate the value-added of domestic production.
Change in real gross domestic product, gross domestic income, and private domestic final purchases
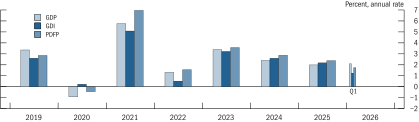
The key identifies bars in order from left to right. GDP is gross domestic product; GDI is gross domestic income; PDFP is private domestic final purchases.
Source: Bureau of Economic Analysis via Haver Analytics.
Among other measures of economic activity, real private domestic final purchases—which comprises consumer spending, business fixed investment, and residential investment and which is usually considered a better indicator of the underlying momentum in the economy than GDP—grew a modest 1.7 percent in the first quarter of this year, somewhat below its pace last year. In addition, gross domestic income—a measure of economic activity conceptually equivalent to GDP but estimated from the total income earned and the costs incurred in producing goods and services—increased a subdued 1.2 percent in the first quarter.
Output in the manufacturing sector has moved up strongly this year, consistent with the pickup in manufacturing new orders (figure 19). The momentum in the sector has been supported by industries producing computer and electronic products, metals, and machinery, suggesting that demand in these industries may be deriving support from AI-related investments and, in some cases, tariffs. In addition, motor vehicle production rebounded after disruptions in the supply of metals and semiconductors constrained production in the fourth quarter of 2025.
Manufacturing new orders
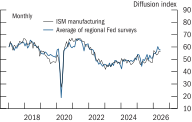
The data extend through June 2026. The regional survey average comprises data from the Dallas Fed's Texas Manufacturing Outlook Survey, the Kansas City Fed's Survey of Tenth District Manufacturers, the New York Fed's Empire State Manufacturing Survey, the Philadelphia Fed's Manufacturing Business Outlook Survey, and the Richmond Fed's Fifth District Survey of Manufacturing Activity. ISM is Institute for Supply Management.
Source: Institute for Supply Management, Manufacturing Report on Business; Federal Reserve Bank of Dallas, Texas Manufacturing Outlook Survey; Federal Reserve Bank of Kansas City, Survey of Tenth District Manufacturers; Federal Reserve Bank of New York, Empire State Manufacturing Survey; Federal Reserve Bank of Philadelphia, Manufacturing Business Outlook Survey; Federal Reserve Bank of Richmond, Fifth District Survey of Manufacturing Activity; all via Haver Analytics.
Consumer spending growth has slowed
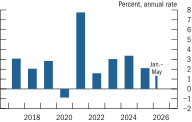
Following two years of robust gains, consumer spending growth slowed to a moderate pace of about 2 percent last year, and it slowed further over the first five months of this year, increasing at an average annualized rate of 1.3 percent (figure 20). The slowdown in consumer spending growth last year and this year can be explained in large part by a moderation in real disposable income growth, which reflects lower net immigration, easing wage growth, and the effects of tariffs and elevated gasoline prices on consumer prices. These headwinds have more than offset support from rising equity prices and the recent pickup in job growth.
Change in real personal consumption expenditures
Source: Bureau of Economic Analysis via Haver Analytics.
Most measures of consumer sentiment moved down after the start of the Middle East conflict, with many survey respondents pointing to elevated gasoline prices as an important factor. Most notably, the Michigan index of consumer sentiment fell to an extraordinarily low level by historical standards (figure 21). By contrast, the Conference Board measure—which relies on questions that are not as directly related to inflation—held up fairly well. In recent weeks, sentiment measures appear to have stabilized or started to rebound, likely in response to the positive news on negotiations between the U.S. and Iran and the decline in gasoline prices. In any case, in recent years low sentiment readings have not presaged particularly weak consumption growth.
Indexes of consumer sentiment
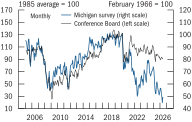
The data extend through June 2026.
Source: University of Michigan Surveys of Consumers; Conference Board.
Broadly, household balance sheets and finances appear healthy. Aggregate wealth is high, and debt remains at moderate levels. Net worth is elevated relative to its 2019 level and has risen in recent years for households across the income distribution. Even so, there are indications that the financial situation of some households is becoming stretched. In particular, auto loan delinquency rates have increased for consumers residing in low- and moderate-income census tracts. For the first quarter, a preliminary estimate of the saving rate stood at 3.9 percent, a fair bit below its pre-pandemic level, which could be another sign of financial pressure on households.
Consumer credit flow picked up, while borrowing costs remained elevated
For most households, consumer credit continued to be generally available through the first quarter of 2026. After growing slowly in January and February, credit card and auto loan balances have picked up in recent months, more notably in the case of credit card loans (figure 22). However, the borrowing costs associated with these loans continued to be elevated. Auto loan rates fell slightly, on net, through May but remained somewhat above the levels seen in 2019.
Consumer credit flows
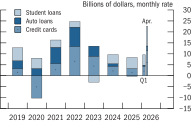
Auto loan balances were little changed in 2025. The data are seasonally adjusted by Federal Reserve Board staff.
Source: Federal Reserve Board, Statistical Release G.19, "Consumer Credit."
Residential investment growth remains weak
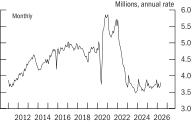
Following a decline in 2025, residential investment fell further in the first quarter of this year, and indicators suggest that activity in the housing market remained stagnant in April and May. Sales of existing homes have been trending sideways for a few years at very low levels and were little changed, on net, over the first five months of this year (figure 23). One factor likely holding down home sales is "rate lock," a phenomenon that discourages homeowners who secured mortgages at rates well below current levels from moving. Even though mortgage rates have moved down somewhat over the past couple of years, the majority of outstanding mortgages still have interest rates below 4 percent—substantially lower than the prevailing 30-year fixed interest rate of 6.4 percent (figure 24 and 25).
Existing home sales
Source: National Association of Realtors via Haver Analytics.
Mortgage interest rates
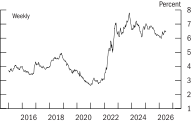
The data are contract rates on 30-year, fixed-rate conventional home mortgage commitments and extend through July 1, 2026.
Source: Freddie Mac Primary Mortgage Market Survey via Haver Analytics.
Distribution of interest rates on outstanding mortgages
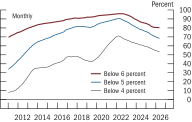
The sample only includes outstanding mortgages current on their payments.
Source: ICE, McDash ®.
Series: Below 6 percent, below 5 percent, and below 4 percent Horizon: January 2011 to May 2026 Description: A line chart with three curves over January 2011 to May 2026. Units are percent, and the data are monthly. The below 6 percent series begins around 70 and rises over the time horizon until 2022, increasing the fastest between January 2011 and December 2014. The series is just below 85 in January 2014 and continues to gradually increase before reaching its peak of around 95 in May 2022. It then decreases steadily, leveling off around 80 in May 2026. The below 5 percent series stays under the below 6 percent series and above the below 4 percent series over the entire horizon. The series begins slightly below 35 in January 2011 and increases at a steady rate, reaching 70 in June 2015. It then increases at a less substantial rate until September 2018, when it hits just below 82 before dipping to around 80 in early 2019. From there, the series rises to a peak of about 90 in April 2022 and then begins to decrease, ending a bit below 70 in May 2026. The below 4 percent series begins just under 10 in January 2011 and increases to about 35 by January 2014. From there, it moves up at a slower rate until hitting about 48 in late 2016 and fluctuating there through early 2018. The series then dips to around 43 in June 2019 before increasing again to a peak of 71 in March 2022. It then begins to decrease again and ends just above 50 in May 2026.
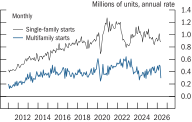
Single-family housing starts have been trending down since early 2024, as high inventories of unsold homes have forestalled new construction (figure 26). Construction of multifamily units—which are predominantly rental units—has returned to more typical levels after a wave of new construction for multifamily units broke ground from 2021 through 2023.
Consistent with the generally weak housing market, market sentiment is downbeat as measured by low readings for builders' ratings of new home sales and homebuyers' sentiment (figure 27). In addition, growth in house prices has slowed further (figure 28). That said, the level of house prices is still well above its pre-pandemic level.
Builder and homebuyer sentiment
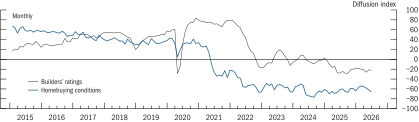
The data extend through June 2026; the June data are preliminary. The builders' ratings of new home sales series measures the percentage of respondents saying current sales conditions are good less the percentage responding conditions are poor. The Michigan survey of homebuying conditions measures the percentage of respondents saying it is a good time to buy less the percentage responding it is a bad time to buy.
Source: National Association of Home Builders (U.S.), Housing Market Index; University of Michigan Surveys of Consumers.
Growth rate in house prices
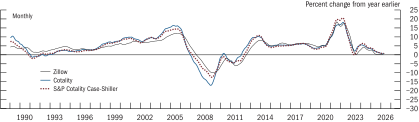
The data for Cotality and S&P Cotality Case-Shiller extend through April 2026.
Source: Cotality, Home Price Index; Zillow, Inc., Real Estate Data; S&P Cotality Case-Shiller U.S. National Home Price Index. The S&P Cotality Case-Shiller index is a product of S&P Dow Jones Indices LLC and/or its affiliates. (For Dow Jones Indices licensing information, see the Data Notes page.)
Capital spending growth has been brisk, reflecting strong demand for investment related to artificial intelligence
After having increased at a solid rate of 5-1/2 percent in 2025, business fixed investment moved up at a robust annual rate of 11 percent in the first quarter of this year (figure 29). Most of the strength in investment appears to be connected to building the infrastructure necessary to support AI services. Construction spending on new data centers has surged since 2022, and announced plans for future data center construction have skyrocketed. As spending on the construction of new data centers has increased, so has spending on the equipment and software required to operate them. Outside of AI-related categories, investment spending—particularly for offices and manufacturing structures—has been fairly weak on net. Still, overall investment has likely benefited from fiscal policy tailwinds following changes in 2025 to reinstate full expensing for certain types of investment.
Change in real business fixed investment
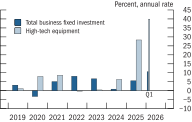
Business fixed investment is known as "private nonresidential fixed investment" in the national income and product accounts. The key identifies bars in order from left to right.
Source: Bureau of Economic Analysis via Haver Analytics.
Drilling and mining investment contracted about 10 percent last year and has increased only modestly so far this year. While oil prices rose sharply in early March, the industry seemed cautious about ramping up investment, likely due to uncertainty about the persistence of elevated prices. That said, the number of active drilling rigs crept up from March through June.
Measures of business sentiment and measures of capital spending plans have been mixed. Analyst expectations of corporate earnings growth are strong, corporate bond spreads are at very low levels, and measures of business uncertainty from financial markets—such as the one-month option-implied volatility on the S&P 500 index, or the VIX—have returned to typical levels after spiking at the start of the Middle East conflict. However, other indicators of trade and geopolitical policy uncertainty are still quite high, and although measures of business sentiment have improved somewhat, they remain on the low side by historical standards.
Business financing conditions have been uneven
Financing conditions for large businesses remained generally accommodative, including financing conditions in capital markets. Gross nonfinancial corporate bond issuance continued at a robust pace in the first half of the year. Net issuance of investment-grade corporate bonds was particularly strong in the first quarter, in part driven by large, publicly traded tech firms, which increased their debt financing of AI infrastructure expansion. Investor sentiment in private credit markets weakened amid net outflows from semi-liquid investment vehicles, but the spillover into broader credit markets was limited.
By contrast, small business financing conditions remained somewhat restrictive. Loan originations declined somewhat, on net, while credit card borrowing by businesses steadily increased in the first half of this year. The increasing level of revolving balances on small business credit card debt, a high-cost credit option, suggests small businesses have been finding it difficult to obtain loans or credit lines from banks. Interest rates on short-term loans and credit cards have fallen somewhat in 2026, but they remain high by recent years' standards. Short-term delinquency rates have begun to tick up after moderating somewhat earlier this year; they now stand above their pre-pandemic levels.
Imports and exports surged in the first quarter
Real imports and exports of goods and services jumped in the first quarter, as the AI-related trade of high-tech goods soared (figure 30). Both nominal imports and exports grew further in April, supported by continued strong trade in high-tech goods and by a jump in U.S. energy exports amid reduced foreign supplies caused by the conflict in the Middle East. All told, net exports subtracted about 0.4 percentage point from GDP growth in the first quarter, and the trade deficit as a share of GDP edged down to 2.1 percent from 2.4 percent in the second half of last year.
Change in real imports and exports of goods and services
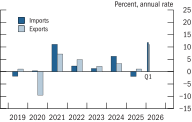
The key identifies bars in order from left to right.
Source: Bureau of Economic Analysis via Haver Analytics.
Federal purchases fell last year but rebounded this year
Federal purchases declined last year because of a reduction in the size of the federal workforce and the government shutdown that temporarily lowered purchases in the fourth quarter. Purchases then rebounded in the first quarter of this year as the effects of the shutdown unwound.7
The budget deficit and federal debt continue to be elevated
In fiscal year 2025 and so far in fiscal 2026, the federal budget deficit—the difference between federal expenditures and receipts—has been around 6 percent of GDP, little changed since fiscal 2023 and notably larger than in the years preceding the pandemic (figure 31). The elevated budget deficit results from both higher noninterest outlays that have outpaced receipts and higher debt-servicing costs that reflect elevated interest rates and a higher level of debt. Reflecting large annual deficits, the ratio of federal debt held by the public to GDP has been moving higher for some time and is now close to its historical peak at the end of World War II (figure 32).
Federal receipts and expenditures
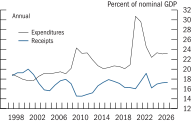
Through 2025, the receipts and expenditures data are on a unified-budget basis and are for fiscal years (October to September); gross domestic product (GDP) is for the 4 quarters ending in Q3. For 2026, receipts and expenditures are annualized for the first 8 months of the fiscal year; GDP is the average of 2025:Q4 and 2026:Q1.
Source: Department of the Treasury, Bureau of the Fiscal Service; Office of Management and Budget and Bureau of Economic Analysis via Haver Analytics.
Federal government debt and net interest outlays
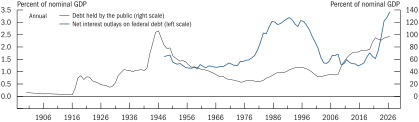
Federal debt held by the public equals federal debt excluding most intragovernmental debt, evaluated at the end of the quarter. Net interest outlays are the cost of servicing the debt held by the public, offset by certain types of interest income the government receives. Through 2025, federal debt data, which begin in 1900, are on a fiscal year basis; net interest outlays data, which begin in 1948, are on a unified-budget basis and are for fiscal years (October to September); and gross domestic product (GDP) is for the 4 quarters ending in Q3. For 2026, federal debt and net interest outlays are annualized for the first 8 months of the fiscal year; GDP is the average of 2025:Q4 and 2026:Q1.
Source: For GDP, Bureau of Economic Analysis via Haver Analytics; for federal debt, Congressional Budget Office and Federal Reserve Board, Statistical Release Z.1, "Financial Accounts of the United States."
State and local government revenue grew moderately
State tax revenue grew moderately last year, rising roughly in line with the broader economy (figure 33). According to the National Association of State Budget Officers, states' total balances—that is, including rainy day fund balances and previous-year surplus funds—are estimated to have declined in fiscal 2026 as a share of general fund spending but remain very elevated relative to pre-pandemic norms. At the local level, growth in property tax receipts was firm in 2025 overall, although growth moved noticeably lower at the end of the year and remained low in early 2026. While the near-term fiscal position of state and local governments remains solid in the aggregate, significant variation exists across jurisdictions.
State and local tax receipts
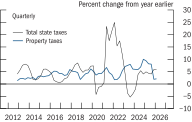
Receipts shown are year-over-year percent changes of 4-quarter moving averages beginning in 2012:Q4. Property taxes are primarily collected by local governments.
Source: U.S. Census Bureau, Quarterly Summary of State and Local Government Tax Revenue.
State and local government spending growth moderated
The rise in state and local government purchases moderated, on average, over 2025 and so far this year relative to the rapid pace of increase in the years immediately following the pandemic. In particular, the pace of hiring by these governments moved down from recent years, returning very roughly to the rate of jobs added during the years before the pandemic (figure 34). Real construction outlays have been edging down, though they remain elevated.
Change in state and local government payroll employment
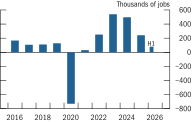
The annual values are the difference between the average level in one year and the average level in the previous year. 2026:H1 data are the annualized change from 2025:Q4 to 2026:Q2.
Source: Bureau of Labor Statistics via Haver Analytics.
A task force will evaluate new data sources
Achieving the Federal Reserve's dual mandate requires high-quality and timely information on economic conditions. Accordingly, the Federal Reserve has commissioned an independent task force to evaluate new information sources and consider methodological changes to improve data gathering. The ultimate goal is to provide the Federal Reserve with more accurate, relevant, contemporaneous, and, perhaps most important, actionable information on the state of the economy.
Financial Developments
The expected path of the federal funds rate shifted up notably...
Market-based measures of the expected path of the federal funds rate showed little change early in 2026 before moving up significantly following the onset of the conflict in the Middle East (figure 35). Earlier in the year, expectations of a decline in inflation and lingering concerns about stabilization in the labor market contributed to the view that the policy rate would fall further toward estimates of its long-run neutral level. Subsequently, however, the policy rate path moved above the levels prevailing at the start of the year. Upward revisions to expectations of the path of the policy rate partly reflected assessments that the Middle East conflict would lead to higher inflation this year and increased confidence in the stability of the U.S. labor market. Federal funds futures quotes suggest that investors currently expect the federal funds rate to increase about 30 basis points above the current effective rate to around 4 percent by year-end 2026. The market-implied path of the federal funds rate also shifted higher for the period beyond 2026.
Market-implied federal funds rate path
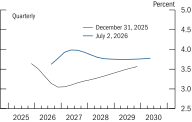
The federal funds rate path is implied by quotes on overnight index swaps—a derivative contract tied to the effective federal funds rate. The implied path as of December 31, 2025, is compared with that as of July 2, 2026. The path is estimated with a spline approach, assuming a term premium of 0 basis points. The December 31, 2025, path extends through 2029:Q4 and the July 2, 2026, path through 2030:Q2.
Source: Bloomberg; Federal Reserve Board staff estimates.
. . . and yields on nominal Treasury securities are higher on net
Since the beginning of the year, yields on nominal Treasury securities have increased, on net, with the largest moves concentrated at shorter maturities. The 2- and 10-year nominal Treasury yields have risen, on net, about 60 basis points and around 35 basis points, respectively (figure 36). Short-term inflation compensation increased sharply after the onset of the conflict in the Middle East but retraced later following headlines of de-escalation. Meanwhile, inflation compensation at longer horizons was a touch lower and stayed at levels consistent with the Committee's inflation objective.
Yields on nominal Treasury securities
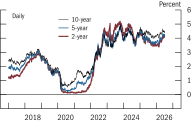
Source: Department of the Treasury via Haver Analytics.
Yields on other long-term debt rose moderately on net
Since the start of the year, corporate bond yields across credit categories have risen moderately, while spreads over comparable-maturity Treasury securities have narrowed somewhat, remaining low by historical standards (figure 37). Meanwhile, yields on municipal bonds were roughly unchanged from the start of the year and remained at elevated levels. Yields on agency mortgage-backed securities—an important factor in the setting of home mortgage interest rates—rose modestly and recorded spreads over Treasury security rates that were little changed, on net, since the start of the year (figure 38).
Corporate bond yields, by securities rating, and municipal bond yield
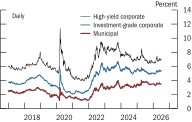
High-yield corporate reflects the effective yield of the ICE Bank of America Merrill Lynch (BofAML) High Yield Index (H0A0). Investment-grade corporate reflects the effective yield of the ICE BofAML triple-B U.S. Corporate Index (C0A4). Municipal reflects the yield to worst of the ICE BofAML U.S. Municipal Securities Index (U0A0).
Source: ICE Data Indices, LLC, used with permission.
Series: High-yield corporate, investment-grade corporate, and municipal Horizon: January 3, 2017, to July 2, 2026 Description: A line chart with three curves over January 3, 2017, to July 2, 2026. Units are percent, and the data are daily. The high-yield corporate series starts at 6 and increases to 8 by the end of 2018. The series gradually decreases to around 5 by the beginning of 2020, jumps to about 11 in early 2020, drops to around 4 by mid-2021, and climbs to 9 by late 2022. The series then declines and fluctuates around 8 before rising briefly to around 9 in 2023 and declining to about 7 by mid-2026. The investment-grade corporate series starts slightly below 4, increases to a bit below 5 by the end of 2018, and declines to around 3 by the beginning of 2020. The series sharply increases to a bit above 5 in early 2020, falls to around 2 by early 2021, rises to about 6 by late 2022, fluctuates between 5 and 7 through late 2024, and hovers between 5 and 6 through mid-2026. The municipal series, following a similar pattern, starts a bit below 3 and fluctuates between 2 and 3 before dropping below 2 from late 2019 through early 2020. The series then increases sharply to a bit below 3 in early 2020, decreases to about 1 by late 2021, and then moves up to about 4 by late 2023. It then drops to around 3 by early 2024, increases to about 4 in 2025, and ends a bit below 4 in mid-2026.
Yield and spread on agency mortgage-backed securities
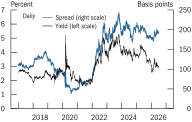
Yield shown is for the uniform mortgage-backed securities 30-year current coupon, the coupon rate at which new mortgage-backed securities would be priced at par, or face, value for dates after May 31, 2019; for earlier dates, the yield shown is for the Fannie Mae 30-year current coupon. Spread shown is to the average of the 5-year and 10-year nominal Treasury yields.
Source: Department of the Treasury; J.P. Morgan. Courtesy of J.P. Morgan Chase & Co., Copyright 2026.
Broad equity price indexes increased, largely driven by robust corporate earnings and optimism about artificial intelligence
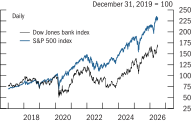
The S&P 500 equity price index has increased about 9 percent since the beginning of the year amid sizable fluctuations and reactions to news about AI-sector developments and the Middle East conflict (figure 39). Reflecting increased investor enthusiasm regarding AI technology and strong earnings growth in the sector, stock prices in the S&P 500 Information Technology industry group are up about 16 percent. The strong stock market performance occurred amid increased volatility, with large price declines from late January through late March. In early February, aggregate stock prices declined amid news about the potential of AI to disrupt certain industries and emerging concerns about over-investment in AI infrastructure. The decline continued in March, as concerns over the inflation outlook emerged from the Middle East conflict. Subsequently, stock prices recovered to reach new record highs, supported by strong corporate earnings results and improved investor risk sentiment. The VIX reached elevated levels of around 30 percent in late March but, on net, has increased only modestly since the beginning of the year and currently sits near the median of its historical distribution (figure 40). (For a discussion of financial stability issues, see the box "Developments Related to Financial Stability.")
Equity prices
Source: S&P Dow Jones Indices LLC via Bloomberg. (For Dow Jones Indices licensing information, see the Data Notes page.)
Series:Dow Jones bank index and S&P 500 index Horizon: January 3, 2017, to July 2, 2026 Description: A line chart with two curves over January 3, 2017, to July 2, 2026. Units for both series have been indexed to 100 based on their respective values on December 31, 2019, and the data are daily. The Dow Jones bank index series starts slightly above 75 and rises to almost 100 by early 2018. The series fluctuates between about 70 and 100 until early 2020, when it plummets to about 50. The series rebounds to slightly below 115 by mid-2021, fluctuates between about 100 and 120 through early 2022, and then falls to a bit above 80 in mid-2022. It fluctuates between around 75 and 100 through late 2023 and rises to around 140 before dropping to about 105 in early 2025. The series continues climbing through mid-2026, ending at about 170. The S&P 500 index series starts around 70 and follows a similar trajectory until early 2020, when the gap between the two series sharply increases to and persists between about 20 and 40 until early 2023, widening to and hovering around 60 through mid-2026. The series finishes slightly above 225.
S&P 500 volatility
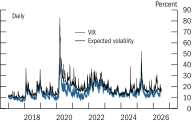
The VIX is an option-implied volatility measure that represents the expected annualized variability of the S&P 500 index over the following 30 days. The expected volatility series shows a forecast of 1-month realized volatility, using a heterogeneous autoregressive model based on 5-minute S&P 500 returns.
Source: Cboe Volatility Index ® (VIX ®) via Bloomberg; LSEG Data & Analytics, DataScope; Federal Reserve Board staff estimates.
Series: VIX and expected volatility Horizon: January 3, 2017, to July 2, 2026 Description: A line chart with two curves over January 3, 2017, to July 2, 2026. Units are percent, and the data are daily. The VIX series starts at and remains around 10 in 2017 before gradually increasing during 2018, aside from spikes to nearly 40 in February 2018 and December 2018, and then declining to about 15 by the end of 2019. The series sharply shoots up to just below 85 in early 2020 and quickly decreases to about 20 by mid-2021, where it then stays relatively constant throughout 2021 before gradually increasing to around 30 in mid-2022. It continues fluctuating between about 20 and 35 through early 2023 and slides to slightly below 15 in mid-2023. After rising to a bit above 20 in late 2023, the series decreases to and stays at around 15 through mid-2024. It spikes to just below 40 in late 2024 and then fluctuates between about 15 and 30, jumping to around 50 in early 2025. It then drops to and fluctuates between about 15 and 30 through mid-2026, with a jump to just above 30 in early 2026, before ending at about 15. The expected volatility series follows a similar trajectory but with a magnitude about 5 to 10 points lower, with the exception of the early 2020 spike, during which the series was about 40 points lower.
Developments Related to Financial Stability
This discussion reviews vulnerabilities in the U.S. financial system. The framework used by the Federal Reserve Board for assessing the resilience of the U.S. financial system focuses on financial vulnerabilities in four broad areas: asset valuations, business and household debt, leverage in the financial sector, and funding risks.
Overall, the U.S. financial system remained sound and resilient, with vulnerabilities roughly unchanged since January. This assessment reflects elevated asset valuations, low levels of total business and household debt, strong bank capital positions, and moderate funding risk, along with high leverage of hedge funds and some strains in private credit funds.
Asset prices remained above levels consistent with their historical relationship to certain fundamentals across several major asset classes. In equity markets, the price of S&P 500 firms relative to analysts' earnings projections stayed in the upper range of its historical distribution. Measures of the equity premium increased from overall low levels late last year amid periods of higher equity and broader market volatility but remained at the lower end of their historical range. Corporate bond and loan spreads remained low by historical standards, although credit concerns increased for riskier debt and spreads widened for speculative-grade technology bonds and leveraged loans. For property markets, house price growth continued to moderate, but the ratio of house prices to rents remained well above historical norms. Commercial real estate markets showed further signs of stabilization, with little change in vacancy rates and rent growth across a broad range of property sectors.
The combined debt of nonfinancial businesses and households as a share of gross domestic product stood at its lowest level since the early 2000s (figure A). Some measures of the aggregate leverage of publicly traded firms stayed high relative to their historical distributions, but solid interest coverage ratios suggest these firms remained well positioned to continue servicing their debt. Debt-servicing capacity was lower among some publicly traded non-investment-grade firms and riskier private firms, especially those relying on floating-rate debt such as leveraged loans and private credit. In the household sector, balance sheets remained strong overall, with most debt being owed by borrowers with strong credit histories. Mortgage credit risk remained low due to large home equity cushions and strong underwriting standards. That said, delinquencies on credit cards and auto loans remained above levels that have prevailed over the past decade.
Nonfinancial business and household debt-to-GDP ratios
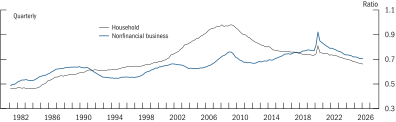
GDP is gross domestic product.
Source: Federal Reserve Board, Statistical Release Z.1, "Financial Accounts of the United States"; Bureau of Economic Analysis, national income and product accounts; Federal Reserve Board staff calculations.
Leverage at hedge funds remained near all-time highs and was concentrated in a small number of large funds. This leverage is associated with a broad range of strategies, including those involving Treasury securities, interest rate derivatives, and equities. Leverage at the largest life insurers stayed well into the upper quartile of its historical distribution, albeit well above regulatory benchmarks. In the banking sector, regulatory measures of bank capital remained near historically high levels. Banks continued to reduce exposure to a potential rise in interest rates as their balance sheets moved toward less interest rate sensitive short-duration securities. These actions helped reduce fair value losses on banks' fixed-rate assets relative to peaks in 2022, but these losses remained sizable. Intermediation activity at broker-dealers continued to support a range of markets, including those for Treasury securities, while their leverage remained roughly unchanged, with asset-to-equity ratios slightly below their historical median.
With regard to funding risks, banks' funding profiles remain mostly unchanged since January. Uninsured deposits have declined for the banking system as a whole since early 2023, and the reduction has been most pronounced among those banks that were most reliant on this source of funding at that time. Outside of the banking system, assets in cash-management vehicles continued to grow, largely driven by government money market funds, which historically have been the least susceptible to large-scale investor redemptions. Finally, some types of private credit vehicles faced increased redemption requests triggered by concerns about reduced returns and the quality of some underlying assets. In most cases, the managers of these funds chose to accommodate redemption requests up to 5 percent of net asset value, and private credit markets continued to function normally.
Major asset markets functioned in an orderly manner
Functioning in the markets for both Treasury securities and equities has been orderly since the start of the year. That said, Treasury securities market liquidity deteriorated amid the heightened volatility following the Middle East conflict. Liquidity recovered in subsequent weeks to near-January levels. Meanwhile, liquidity conditions in equity markets have deteriorated slightly since the start of the year and have remained low, with a notable feature being a low reading on market depth—a measure of the availability of contracts at the best quoted prices. Corporate and municipal bond markets functioned in an orderly manner.
Short-term money market conditions remained stable
Conditions in overnight bank funding and repurchase agreement (repo) markets remained stable but have softened somewhat since the start of the year. The Federal Reserve continued to purchase Treasury bill securities to ensure an ample supply of reserves, and as a result, reserve balances have increased slightly since the beginning of January. The effective federal funds rate decreased, on net, by 1 basis point below the interest on reserve balances (IORB) rate to 2 basis points below the IORB rate, and other unsecured rates also decreased, with limited volatility. The Secured Overnight Financing Rate declined relative to the IORB rate and exhibited limited volatility on Treasury settlement days and quarter-ends. Over the period, there was limited uptake at the overnight reverse repurchase agreement facility or of standing repo operations. Overall, conditions in money markets suggest that reserve balances remain within the range consistent with ample reserves. (See the box "Developments in the Federal Reserve's Balance Sheet and Money Markets.")
Following the onset of the Middle East conflict, spreads on lower-rated commercial paper widened but have since returned to historically normal ranges as geopolitical tensions eased. Money market mutual funds maintained near-record levels of assets under management, as the yields they offered to potential customers continued to be more attractive than interest rates available on bank deposits.
Bank credit expanded at a strong pace
Banks' core loan holdings increased at a 5.5 percent annualized rate in the first quarter, above the growth rate in 2025, and expanded at a similar pace during the second quarter (figure 41). Banks' responses to the April 2026 Senior Loan Officer Opinion Survey on Bank Lending Practices indicated, over the first quarter of 2026, easier lending standards across loan categories for the third consecutive quarter and stronger demand, on net, for the fourth consecutive quarter, supporting the uptick in loan growth. Measures of credit quality, including loan delinquency rates and loan loss provisioning across loan categories, were little changed, on average, over the first quarter of 2026. Bank profitability measures were also little changed, on net, in the first quarter (figure 42).
Ratio of total commercial bank credit to nominal gross domestic product
Source: Federal Reserve Board, Statistical Release H.8, "Assets and Liabilities of Commercial Banks in the United States"; Bureau of Economic Analysis via Haver Analytics.
Profitability of bank holding companies
Source: Federal Reserve Board, Form FR Y-9C, Consolidated Financial Statements for Holding Companies.
The M2 measure of money grew in line with trends observed in the 2010s
A measure of the stock of money potentially has a role to play in the evaluation of financial and economic conditions. Although it is difficult to measure the stock of money in the modern economy, one of a number of series traditionally used to provide an empirical approximation to the concept of the stock of money is the M2 monetary aggregate. During the first five months of the year, M2—which consists of currency, liquid deposits (deposits readily usable in transactions), small time deposits, and retail money funds—was 4.7 percent higher, on average, than its level from a year earlier. The rates of increase in M2 seen so far this year have been closer to the range typically observed in the 2010s and stand in contrast to the first half of the current decade, which saw high double-digit growth rates of M2 followed by a period of negative growth rates. The sizable increase in the public's holdings of real money balances that took place during the pandemic has largely been unwound. In the first quarter of 2026, M2 velocity—the ratio of nominal GDP to the quarterly average of M2—was only slightly below its level in the fourth quarter of 2019.
International Developments
Foreign economic growth slowed in the first half of 2026
Economic activity abroad has been affected recently by U.S. trade policy, the AI boom, and the emergence of the Middle East conflict. Real GDP growth abroad stepped down in the first quarter from its trend pace in the second half of last year, largely reflecting a sharp contraction in Mexico and stagnant activity in Canada, with U.S. sectoral tariffs continuing to weigh on manufacturing in these economies. In most euro-area countries, growth remained lackluster, as uncertainty weighed on investment and exports continued to be weak. By contrast, economic activity in several Asian economies—particularly in Taiwan and South Korea—remained robust, on strong high-tech exports linked to soaring AI-related investment, especially in the U.S. In China, growth picked up to a solid pace, with strong exports and industrial production offsetting weakness in domestic demand.
Recent indicators point to continued subdued growth abroad in the second quarter, with the Middle East conflict and supply disruptions associated with the closure of the Strait of Hormuz weighing on activity through higher energy costs, longer supplier delivery times, and weaker confidence. These effects appear most pronounced in regions reliant on energy imports from the Middle East, particularly lower-income Asian economies. In Europe and Japan, activity indicators, including industrial production and retail sales, have also softened. At the same time, in a few Asian economies with large high-tech sectors, ongoing investment in AI capacity in the U.S. and elsewhere has continued to lift tech production and exports, helping to cushion the headwinds from the Middle East conflict.
Inflation abroad rose notably amid higher energy costs
Foreign headline inflation has increased since the start of the Middle East conflict, mainly reflecting the sharp rise in retail energy prices in both advanced foreign economies (AFEs) and emerging market economies (EMEs) (figure 43). Foreign producer prices have also increased notably in recent months, especially for industries exposed to disruptions from the Middle East conflict or benefiting from strong AI-related demand. Conversely, inflation in China has remained low, at around 1 percent, as the weakness in the property sector continues to limit price pressures.
Consumer price inflation in foreign economies
The advanced foreign economy (AFE) aggregate is the average of Canada, the euro area, Japan, and the U.K., weighted by shares of U.S. non-oil goods imports. The emerging market economy (EME) aggregate is the average of Argentina, Brazil, Chile, Colombia, Hong Kong, India, Indonesia, Israel, Malaysia, Mexico, the Philippines, Russia, Saudi Arabia, Singapore, South Korea, Taiwan, Thailand, and Vietnam, weighted by shares of U.S. non-oil goods imports. The foreign aggregate is the import-weighted average of all aforementioned economies. The inflation measure is the Harmonised Index of Consumer Prices for the euro area and the consumer price index for the other economies.
Source: Federal Reserve Board staff calculations; Haver Analytics.
Several foreign central banks raised policy rates or signaled policy tightening amid rising inflationary pressures
At the beginning of the year, market participants generally had expected foreign central banks to keep policy rates on hold or ease them modestly further, reflecting the significant progress in reestablishing price stability. Since the onset of the Middle East conflict, however, policy rate paths implied by financial market pricing indicate that markets expect AFE central banks to raise interest rates (figure 44). Indeed, several central banks, including the Bank of Japan, the European Central Bank, and the Reserve Bank of Australia, have already responded to higher inflation by raising policy rates. Meanwhile, other central banks have emphasized inflation developments and risks in their communications, along with the importance of keeping inflation expectations anchored, signaling that they might raise policy rates despite weaker growth prospects.
24-month policy expectations for selected advanced foreign economies
The data are weekly averages of daily 24-month market-implied central bank policy rates and extend through July 2, 2026. The 24-month policy rates are implied by quotes on overnight index swaps tied to the policy rates.
Source: Bloomberg; Federal Reserve Board staff calculations.
Equity prices rose even as sovereign bond yields increased...
Since early 2026, near-dated sovereign yields have risen in many AFEs, as markets anticipated higher policy rates in response to inflationary pressures resulting from the conflict in the Middle East (figure 45). Nonetheless, most major foreign equity price indexes increased briskly, on net, in the first half of 2026, supported by improved corporate earnings, AI optimism, and strong GDP growth in higher-income Asia (figure 46). EMEs have seen notable portfolio capital outflows since the start of the conflict.
Nominal 2-year government bond yields in selected advanced foreign economies
The data are weekly averages of daily benchmark yields and extend through July 2, 2026.
Source: Bloomberg.
Series:Germany, U.K., Canada, and Japan Horizon: January 4, 2019, to July 2, 2026 Description: A line chart with four curves over January 4, 2019, to July 2, 2026. The units are percent, and the data are weekly averages of daily benchmark yields. The curves for Germany, the U.K., Canada, and Japan all vary significantly at short time scales. The Germany series begins around negative 0.5, fluctuates between negative 0.5 and negative 1 throughout 2020 and 2021, and climbs rapidly in early 2022 to above 0. The series then rises to more than 2.5 by early 2023, peaking a bit above 3 before slowly falling back to around 2 by late 2024. The series remains around that level through 2025 and finishes at around 2.5. The U.K. series begins somewhat below 1, slumps to just below 0 by mid-2020, and climbs steadily to above 3 by late 2022 before reaching its peak in 2023, a bit below 5.5. The series then declines slowly to about 3.5 by the start of 2026 and ends slightly above 4. The Canada series begins slightly below 2 and falls rapidly to somewhat above 0 in early 2020. It remains roughly at that level through late 2021 before climbing up to around 4 by the end of 2022, reaching a peak near 5 by late 2023. The series then declines gradually throughout 2024 and 2025, ending a bit below 3. The Japan series begins slightly below 0 and remains at about that level through early 2023 before rising gradually and climbing to around 0.5 by late 2024. The series continues to increase slowly, peaking and finishing a bit below 1.5 percent.
Equity indexes for selected foreign economies
The data are weekly averages of daily data and extend through July 2, 2026.
Source: For the euro area, Dow Jones Euro Stoxx Index; for Japan, Tokyo Stock Price Index; for China, Shanghai Composite Index; for the U.K., FTSE 100 Index; all via Bloomberg. (For Dow Jones Indices licensing information, see the Data Notes page.)
Series: Euro area, Japan, U.K., and China Horizon: January 4, 2019, to July 2, 2026 Description: A line chart with four curves over January 4, 2019, to July 2, 2026. The units are indexed with the week ending January 4, 2019, equal to 100, and the data are weekly averages of daily data. The euro-area series begins at 100, increases to nearly 130 before plunging to almost 80 in early 2020, climbs to nearly 150 by late 2021, and then drops to around 110 by late 2022. The series then rises to around 140 by mid-2023 before dropping to around 130 by late 2023 and fluctuates between about 140 and 160 over 2024. The series then rises to nearly 175 over the first three months of 2025 before plunging to about 150 in April, retracing and climbing to about 200 by February 2026. It then dips somewhat to around 180 in March and rebounds, finishing just above 200. The Japan series tracks closely with that of the euro area through 2020, though the Japan series runs about 5 to 10 points lower in 2019. It then increases to and fluctuates between around 120 and 135 through 2022 before rising rapidly to around 160 by the end of 2023. The series then rises to about 195 by mid-2024, falls to around 160 before climbing to and hovering between about 175 and 185 through early 2025, drops sharply to a bit above 160 in April, and steadily increases to just below 260 by February 2026. Similar to the euro area, the series then plunges somewhat before rebounding and finishing just below 270. The U.K. series also tracks closely with that of the euro area before 2020. The series drops to around 75 in early 2020, gradually rises to around 110 by the end of 2021, fluctuates between about 105 and 115 in 2022, and increases to and fluctuates between approximately 110 and 125 from 2023 through the end of 2024. It then climbs to about 130 in early 2025, drops to a bit above 115 in April, retraces and rises to a bit below 150 by the end of 2025, declines slightly in early 2026, and rebounds, finishing around 160. The China series moves broadly in line with the other series before 2020 and rises slightly above the others through 2021, when it reaches a peak of nearly 150. The series then slowly declines through mid-2024, reaching a nadir of around 110 before rising sharply to just above 125. It then climbs to just below 160 by the end of 2025 before dipping slightly in early 2026 and retracing to finish a bit above 160.
. . . and the exchange value of the dollar also rose modestly
Since the beginning of the year, the broad dollar index—a measure of the exchange value of the dollar against a trade-weighted basket of foreign currencies—increased modestly, on net, despite some volatility amid Middle East developments (figure 47). The dollar remained strong in real terms relative to its historical average.
U.S. dollar exchange rate index
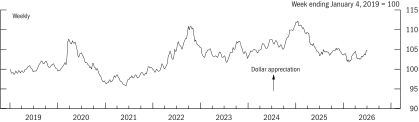
The data, which are in foreign currency units per dollar, are weekly averages of daily values of the broad dollar index and extend through July 2, 2026. As indicated by the arrow, increases in the data reflect U.S. dollar appreciation and decreases reflect U.S. dollar depreciation.
Source: Federal Reserve Board, Statistical Release H.10, "Foreign Exchange Rates."
Footnotes
Monetary Policy
The Federal Open Market Committee held the federal funds rate steady
The Federal Open Market Committee (FOMC) has maintained the target range for the federal funds rate at 3-1/2 to 3-3/4 percent since the beginning of the year, in support of the Federal Reserve's dual mandate (figure 48). Economic activity is expanding at a solid pace despite elevated uncertainty that owes, in part, to the conflict in the Middle East. Productivity growth and capital investment are strong. Job gains have kept pace with the workforce, and the unemployment rate has changed little. Inflation remains elevated relative to the Committee's 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability.
Selected interest rates
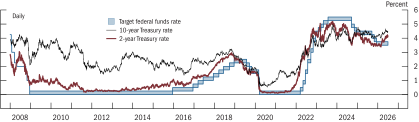
The 2-year and 10-year Treasury rates are the constant-maturity yields based on the most actively traded securities.
Source: Department of the Treasury; Federal Reserve Board.
The Federal Reserve continued to conduct reserve management purchases to keep reserves within the ample range
At the December 2025 meeting, the FOMC judged that reserve balances had declined to ample reserve levels and initiated the purchases of shorter-term Treasury securities to maintain an ample supply of reserves on an ongoing basis. At the June meeting, the Committee reaffirmed its policy of maintaining ample reserves in the banking system.
Since early January 2026, the FOMC has continued reserve management purchases of Treasury bills, and as a result, the total size of the balance sheet has ticked up (figure 49). Reserve balances—the largest liability item on the Federal Reserve's balance sheet—have increased since early January to a level of about $3.1 trillion and remain within the ample range. (See the box "Developments in the Federal Reserve's Balance Sheet and Money Markets.")
Federal Reserve assets and liabilities
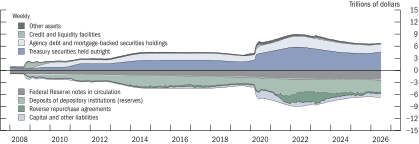
"Other assets" includes repurchase agreements, FIMA (Foreign and International Monetary Authorities) repurchase agreements, and unamortized premiums and discounts on securities held outright. "Credit and liquidity facilities" consists of primary, secondary, and seasonal credit; term auction credit; central bank liquidity swaps; support for Maiden Lane, Bear Stearns Companies, Inc., and AIG; and other credit and liquidity facilities, including the Primary Dealer Credit Facility, the Asset-Backed Commercial Paper Money Market Mutual Fund Liquidity Facility, the Commercial Paper Funding Facility, the Term Asset-Backed Securities Loan Facility, the Primary and Secondary Market Corporate Credit Facilities, the Paycheck Protection Program Liquidity Facility, the Municipal Liquidity Facility, and the Main Street Lending Program. "Agency debt and mortgage-backed securities holdings" includes agency residential mortgage-backed securities and agency commercial mortgage-backed securities. "Capital and other liabilities" includes the U.S. Treasury General Account and the U.S. Treasury Supplementary Financing Account. The key identifies shaded areas in order from top to bottom. The data extend through July 1, 2026.
Source: Federal Reserve Board, Statistical Release H.4.1, "Factors Affecting Reserve Balances."
Developments in the Federal Reserve's Balance Sheet and Money Markets
The Federal Open Market Committee (FOMC) continued reserve management purchases (RMPs) to maintain an ample supply of reserves. Since early January 2026, the Federal Reserve's System Open Market Account (SOMA) portfolio has purchased nearly $250 billion in Treasury bills of which approximately $160 billion are RMPs and $90 billion are reinvestments from principal payments of agency mortgage-backed securities, consistent with the Committee's intention to hold primarily Treasury securities in the SOMA. As a result, Federal Reserve assets have increased about $150 billion, bringing the total size of the balance sheet to $6.7 trillion (table A and figure A). Reserves, the largest liability item on the Federal Reserve's balance sheet, have grown $54 billion to a level of about $3.1 trillion (figure B). Usage of the overnight reverse repurchase agreement (ON RRP) facility remained near zero on most days, and standing repurchase agreement operations were tapped when economically sensible.
Table A. Balance sheet comparison
Billions of dollars
Federal Reserve assets
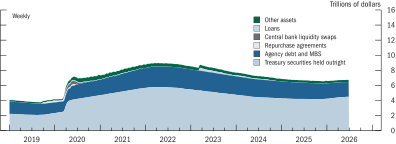
The data extend through July 1, 2026. MBS is mortgage-backed securities. The key identifies shaded areas in order from top to bottom.
Source: Federal Reserve Board, Statistical Release H.4.1, "Factors Affecting Reserve Balances."
Federal Reserve liabilities
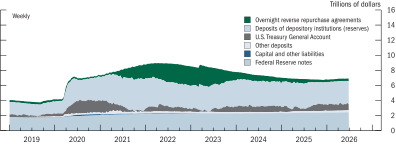
The data extend through July 1, 2026. "Capital and other liabilities" includes the liability for earnings remittances due to the U.S. Treasury and contributions from the U.S. Treasury; the sum is negative from June 2023 onward because of the deferred asset that the Federal Reserve reports. The key identifies shaded areas in order from top to bottom.
Source: Federal Reserve Board, Statistical Release H.4.1, "Factors Affecting Reserve Balances."
Overnight money markets were stable, with conditions softening somewhat since the beginning of the year and RMPs effectively accommodating seasonal fluctuations in nonreserve liabilities, such as April and June tax inflows. The Federal Reserve's administered rates—the interest rate paid on reserve balances and the ON RRP offering rate—remained highly effective at maintaining the effective federal funds rate within the target range.
Since early January, the consolidated deferred asset of the Federal Reserve System has decreased $7 billion to a level of around $236 billion. Net income and remittances to the U.S. Treasury are calculated at the Federal Reserve Bank level. As a result, the Systemwide deferred asset is an aggregation of each Reserve Bank whose net income is yet to extinguish its respective accumulated deferred asset. By contrast, Reserve Banks that no longer have a deferred asset have collectively remitted around $6 billion to the U.S. Treasury this year. Negative net income and the associated deferred asset do not affect the Federal Reserve's conduct of monetary policy.
A task force will review balance sheet policy
One of the new independent task forces will explore the benefits and risks associated with the current ample-reserves regime and will examine considerations related to the composition of the Federal Reserve's balance sheet as part of an assessment of alternative frameworks for the conduct and operation of monetary policy.
The Federal Open Market Committee will continue to consider a broad range of information sources
The FOMC considers a broad range of information sources, including contemporaneous market signals, official government statistics, nontraditional data sources, and updates provided by business contacts and other informed parties around the country, as summarized in the Beige Book. The Federal Reserve also regularly hears from a broad range of participants in the U.S. economy about how monetary policy affects people's daily lives. For example, the Federal Reserve has continued to gather insights into these matters through the Federal Reserve System's community development outreach.
Policymakers routinely consult information derived from the analysis of various monetary policy rules. However, simple rules may not be able to capture all of the considerations that go into the formation of appropriate monetary policy. Practical considerations make it undesirable, at present, for the FOMC to adhere strictly to the prescriptions of any single rule. That said, some principles of effective monetary policy can be better understood by examining these prescriptive rules.(See the box "Monetary Policy Rules in the Current Environment.")
A task force will explore Federal Reserve communications
One of the new independent task forces will explore Federal Reserve communications, including the Summary of Economic Projections, with the possibility of suggesting changes to current arrangements.
Monetary Policy Rules in the Current Environment
Simple interest rate rules relate a policy interest rate, such as the federal funds rate, to a small number of other economic variables—typically including measures of the current deviation of inflation from its target value and of resource slack in the economy. This discussion provides an update to the prescriptions of several simple policy rules that policymakers regularly consult as part of their monetary policy deliberations and that have been considered in past Monetary Policy Reports. The simple policy rules covered here called for levels of the policy rate in the first quarter of this year that were a little above the current target range for the federal funds rate of 3-1/2 to 3-3/4 percent, reflecting the fact that the measure of inflation used to calculate the prescriptions of these rules has moved up. However, the prescriptions shown here ignore that the economy would have evolved differently if the policy rate had followed one of the paths prescribed by the rules, and, hence, these prescriptions should be interpreted with care.
In many economic models, desirable economic outcomes can be achieved over time if monetary policy responds to changes in economic conditions in a manner that is predictable and adheres to some key design principles—including the notion that the policy rate should be adjusted sufficiently to ensure a return of inflation to the central bank's longer-run price-stability objective and to anchor longer-term inflation expectations at levels consistent with that objective. Simple policy rules do, however, also have important limitations. For example, they mechanically respond to only a small set of economic variables and thus necessarily involve abstracting from many of the factors that the Federal Open Market Committee (FOMC) considers when it assesses the appropriate setting of the policy rate. Relatedly, although simple policy rules typically respond to particular measures of inflation and resource slack, other measures could be used to calculate the rule prescriptions. Most simple policy rules also require measures of unobservable variables, like the neutral real interest rate and unemployment rate in the longer run, which can only be estimated with considerable uncertainty. In light of these and other limitations, achieving the potential benefits associated with using policy rules as part of a policy strategy requires efforts to promote the public's understanding of monetary policy strategy and the incorporation of timely data to measure the factors entering policy rules and the broader strategy. The recently announced task forces will be considering matters related to this point.
Selected Policy Rules: Descriptions
Table A shows the well-known Taylor (1993) rule, the "adjusted Taylor (1993)" rule, the "balanced approach" rule, and the "first difference" rule.1 All rules considered here feature the difference between the annual change in the core personal consumption expenditures (PCE) price index and the FOMC's longer-run objective of 2 percent.2 With the exception of the first-difference rule, all rules use the unemployment rate gap—measured as the difference between an estimate of the rate of unemployment in the longer run ($$ u_t^{LR}$$) and the current unemployment rate—and an estimate of the neutral real interest rate in the longer run ($$ r_t^{LR}$$).3 The first-difference rule uses the change in the unemployment rate over the past four quarters, rather than the unemployment rate gap, and the value of the policy rate in the preceding quarter, rather than the neutral interest rate in the long run.4
Table A. Monetary policy rules
Unlike the other simple rules featured here, the adjusted Taylor (1993) rule recognizes that the federal funds rate cannot be reduced materially below the effective lower bound (ELB). By contrast, the standard Taylor (1993) rule prescribed policy rates that, during the pandemic-induced recession, were far below zero. To make up for the cumulative shortfall in policy accommodation following a period during which the federal funds rate is constrained by its ELB, the adjusted Taylor (1993) rule prescribed delaying the return of the policy rate to the (positive) levels prescribed by the standard Taylor (1993) rule.
Selected Policy Rules: Prescriptions
Figure A shows historical prescriptions for the federal funds rate under the four simple rules alongside the actual target federal funds rate. For each quarterly period, the figure reports the policy rates prescribed by the rules, taking as given the prevailing economic conditions and, where applicable, survey-based estimates of $$ u_t^{LR}$$ and $$ r_t^{LR}$$ at the time. All of the rules considered called for highly accommodative monetary policy in response to the pandemic-driven recession, followed by tighter policy as inflation picked up and labor market conditions strengthened. Starting around 2023, the prescribed values associated with most of the rules declined, as inflation eased and the unemployment rate increased. Subsequently, because the annual change in the core PCE price index has been somewhat above 2 percent, the prescriptions of the simple policy rules have also remained somewhat elevated relative to their pre-2020 levels.
Historical federal funds rate prescriptions from simple policy rules
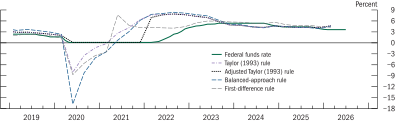
The rules use historical values of core personal consumption expenditures (PCE) inflation, the unemployment rate, and, where applicable, the midpoint of the target range for the federal funds rate constructed as the average of the lower and upper limits of the target range. Quarterly projections of longer-run values for the federal funds rate, the unemployment rate, and inflation used in the computation of the rules' prescriptions are interpolations to quarterly values of projections from the Survey of Market Expectations. The rules' prescriptions are quarterly, and the federal funds rate data are the monthly average of the daily midpoint of the target range for the federal funds rate and extend through June 2026.
Source: For core PCE inflation, PCEPILFE; for the unemployment rate, UNRATE; for the lower and upper limits of the federal funds target range, DFEDTARL and DFEDTARU, respectively; all from Federal Reserve Bank of St. Louis, Federal Reserve Economic Data; Federal Reserve Bank of New York, Survey of Market Expectations; Federal Reserve Board staff estimates.
Summary of Economic Projections
A version of the following material was released after the conclusion of the June 16–17, 2026, meeting of the Federal Open Market Committee. A version of the following material was released after the conclusion of the June 16–17, 2026, meeting of the Federal Open Market Committee.
In conjunction with the Federal Open Market Committee (FOMC) meeting held on June 16–17, 2026, meeting participants, aside from the Chairman, submitted their projections of the most likely outcomes for real gross domestic product (GDP) growth, the unemployment rate, and inflation for each year from 2026 to 2028 and over the longer run. Each participant's projections were based on information available at the time of the meeting, together with her or his assessment of appropriate monetary policy—including a path for the federal funds rate and its longer-run value—and assumptions about other factors likely to affect economic outcomes. The longer-run projections represent each participant's assessment of the value to which each variable would be expected to converge, over time, under appropriate monetary policy and in the absence of further shocks to the economy. "Appropriate monetary policy" is defined as the future path of policy that each participant deems most likely to foster outcomes for economic activity and inflation that best satisfy his or her individual interpretation of the statutory mandate to promote maximum employment and price stability.
Table 1. Economic projections of Federal Reserve Board members and Federal Reserve Bank presidents, presidents, under their individual assumptions of projected appropriate monetary policy, June 2026
Medians, central tendencies, and ranges of economic projections, 2026–28 and over the longer run
Definitions of variables and other explanations are in the notes to table 1. The data for the actual values of the variables are annual.
FOMC participants' assessments of appropriate monetary policy: Midpoint of target range or target level for the federal funds rate
Each shaded circle indicates the value (rounded to the nearest 1/8 percentage point) of an individual participant's judgment of the midpoint of the appropriate target range for the federal funds rate or the appropriate target level for the federal funds rate at the end of the specified calendar year or over the longer run.
Distribution of participants' projections for the change in real GDP, 2026–28 and over the longer run
Definitions of variables and other explanations are in the notes to table 1.
Distribution of participants' projections for the unemployment rate, 2026–28 and over the longer run
Definitions of variables and other explanations are in the notes to table 1.
Distribution of participants' projections for PCE inflation, 2026–28 and over the longer run
Definitions of variables and other explanations are in the notes to table 1.
Distribution of participants' projections for core PCE inflation, 2026–28
Definitions of variables and other explanations are in the notes to table 1.
Distribution of participants' judgments of the midpoint of the appropriate target range for the federal funds rate or the appropriate target level for the federal funds rate, 2026–28 and over the longer run
Definitions of variables and other explanations are in the notes to table 1.
Uncertainty and risks in projections of GDP growth
The blue and red lines in the top panel show actual values and median projected values, respectively, of the percent change in real gross domestic product (GDP) from the fourth quarter of the previous year to the fourth quarter of the year indicated. The confidence interval around the median projected values is assumed to be symmetric and is based on root mean squared errors of various private and government forecasts made over the previous 20 years; more information about these data is available in table 2. Because current conditions may differ from those that prevailed, on average, over the previous 20 years, the width and shape of the confidence interval estimated on the basis of the historical forecast errors may not reflect FOMC participants' current assessments of the uncertainty and risks around their projections; these current assessments are summarized in the lower panels. Generally speaking, participants who judge the uncertainty about their projections as "broadly similar" to the average levels of the past 20 years would view the width of the confidence interval shown in the historical fan chart as largely consistent with their assessments of the uncertainty about their projections. Likewise, participants who judge the risks to their projections as "broadly balanced" would view the confidence interval around their projections as approximately symmetric. For definitions of uncertainty and risks in economic projections, see the box "Forecast Uncertainty."
Uncertainty and risks in projections of the unemployment rate
The blue and red lines in the top panel show actual values and median projected values, respectively, of the average civilian unemployment rate in the fourth quarter of the year indicated. The confidence interval around the median projected values is assumed to be symmetric and is based on root mean squared errors of various private and government forecasts made over the previous 20 years; more information about these data is available in table 2. Because current conditions may differ from those that prevailed, on average, over the previous 20 years, the width and shape of the confidence interval estimated on the basis of the historical forecast errors may not reflect FOMC participants' current assessments of the uncertainty and risks around their projections; these current assessments are summarized in the lower panels. Generally speaking, participants who judge the uncertainty about their projections as "broadly similar" to the average levels of the past 20 years would view the width of the confidence interval shown in the historical fan chart as largely consistent with their assessments of the uncertainty about their projections. Likewise, participants who judge the risks to their projections as "broadly balanced" would view the confidence interval around their projections as approximately symmetric. For definitions of uncertainty and risks in economic projections, see the box "Forecast Uncertainty."
Uncertainty and risks in projections of PCE inflation
The blue and red lines in the top panel show actual values and median projected values, respectively, of the percent change in the price index for personal consumption expenditures (PCE) from the fourth quarter of the previous year to the fourth quarter of the year indicated. The confidence interval around the median projected values is assumed to be symmetric and is based on root mean squared errors of various private and government forecasts made over the previous 20 years; more information about these data is available in table 2. Because current conditions may differ from those that prevailed, on average, over the previous 20 years, the width and shape of the confidence interval estimated on the basis of the historical forecast errors may not reflect FOMC participants' current assessments of the uncertainty and risks around their projections; these current assessments are summarized in the lower panels. Generally speaking, participants who judge the uncertainty about their projections as "broadly similar" to the average levels of the past 20 years would view the width of the confidence interval shown in the historical fan chart as largely consistent with their assessments of the uncertainty about their projections. Likewise, participants who judge the risks to their projections as "broadly balanced" would view the confidence interval around their projections as approximately symmetric. For definitions of uncertainty and risks in economic projections, see the box "Forecast Uncertainty."
Diffusion indexes of participants' uncertainty assessments
For each SEP, participants provided responses to the question "Please indicate your judgment of the uncertainty attached to your projections relative to the levels of uncertainty over the past 20 years." Each point in the diffusion indexes represents the number of participants who responded "Higher" minus the number who responded "Lower," divided by the total number of participants. Figure excludes March 2020 when no projections were submitted.
Diffusion indexes of participants' risk weightings
For each SEP, participants provided responses to the question "Please indicate your judgment of the risk weighting around your projections." Each point in the diffusion indexes represents the number of participants who responded "Weighted to the Upside" minus the number who responded "Weighted to the Downside," divided by the total number of participants. Figure excludes March 2020 when no projections were submitted.
Uncertainty and risks in projections of the federal funds rate
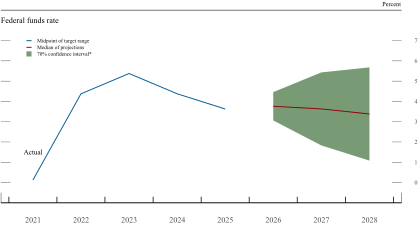
The blue and red lines are based on actual values and median projected values, respectively, of the Committee's target for the federal funds rate at the end of the year indicated. The actual values are the midpoint of the target range; the median projected values are based on either the midpoint of the target range or the target level. The confidence interval around the median projected values is based on root mean squared errors of various private and government forecasts made over the previous 20 years. The confidence interval is not strictly consistent with the projections for the federal funds rate, primarily because these projections are not forecasts of the likeliest outcomes for the federal funds rate, but rather projections of participants' individual assessments of appropriate monetary policy. Still, historical forecast errors provide a broad sense of the uncertainty around the future path of the federal funds rate generated by the uncertainty about the macroeconomic variables as well as additional adjustments to monetary policy that may be appropriate to offset the effects of shocks to the economy.
Table 2. Average Historical Projection Error Ranges
Percentage points
Forecast Uncertainty
The economic projections provided by the members of the Board of Governors and the presidents of the Federal Reserve Banks inform discussions of monetary policy among policymakers and can aid public understanding of the basis for policy actions. Considerable uncertainty attends these projections, however. The economic and statistical models and relationships used to help produce economic forecasts are necessarily imperfect descriptions of the real world, and the future path of the economy can be affected by myriad unforeseen developments and events. Thus, in setting the stance of monetary policy, participants consider not only what appears to be the most likely economic outcome as embodied in their projections, but also the range of alternative possibilities, the likelihood of their occurring, and the potential costs to the economy should they occur.
Table 2 summarizes the average historical accuracy of a range of forecasts, including those reported in past Monetary Policy Reports and those prepared by the Federal Reserve Board's staff in advance of meetings of the Federal Open Market Committee (FOMC). The projection error ranges shown in the table illustrate the considerable uncertainty associated with economic forecasts. For example, suppose a participant projects that real gross domestic product (GDP) and total consumer prices will rise steadily at annual rates of, respectively, 3 percent and 2 percent. If the uncertainty attending those projections is similar to that experienced in the past and the risks around the projections are broadly balanced, the numbers reported in table 2 would imply a probability of about 70 percent that actual GDP would expand within a range of 1.3 to 4.7 percent in the current year, 1.2 to 4.8 percent in the second year, and 0.8 to 5.2 percent in the third year. The corresponding 70 percent confidence intervals for overall inflation would be 1.0 to 3.0 percent in the current year, 0.4 to 3.6 percent in the second year, and 0.6 to 3.4 percent in the third year. Figures 4.A through 4.C illustrate these confidence bounds in "fan charts" that are symmetric and centered on the medians of FOMC participants' projections for GDP growth, the unemployment rate, and inflation. However, in some instances, the risks around the projections may not be symmetric. In particular, the unemployment rate cannot be negative; furthermore, the risks around a particular projection might be tilted to either the upside or the downside, in which case the corresponding fan chart would be asymmetrically positioned around the median projection.
Because current conditions may differ from those that prevailed, on average, over history, participants provide judgments as to whether the uncertainty attached to their projections of each economic variable is greater than, smaller than, or broadly similar to typical levels of forecast uncertainty seen in the past 20 years, as presented in table 2 and reflected in the widths of the confidence intervals shown in the top panels of figures 4.A through 4.C. Participants' current assessments of the uncertainty surrounding their projections are summarized in the bottom-left panels of those figures. Participants also provide judgments as to whether the risks to their projections are weighted to the upside, are weighted to the downside, or are broadly balanced. That is, while the symmetric historical fan charts shown in the top panels of figures 4.A through 4.C imply that the risks to participants' projections are balanced, participants may judge that there is a greater risk that a given variable will be above rather than below their projections. These judgments are summarized in the lower-right panels of figures 4.A through 4.C.
As with real activity and inflation, the outlook for the future path of the federal funds rate is subject to considerable uncertainty. This uncertainty arises primarily because each participant's assessment of the appropriate stance of monetary policy depends importantly on the evolution of real activity and inflation over time. If economic conditions evolve in an unexpected manner, then assessments of the appropriate setting of the federal funds rate would change from that point forward. The final line in table 2 shows the error ranges for forecasts of short-term interest rates. They suggest that the historical confidence intervals associated with projections of the federal funds rate are quite wide. It should be noted, however, that these confidence intervals are not strictly consistent with the projections for the federal funds rate, as these projections are not forecasts of the most likely quarterly outcomes but rather are projections of participants' individual assessments of appropriate monetary policy and are on an end-of-year basis. However, the forecast errors should provide a sense of the uncertainty around the future path of the federal funds rate generated by the uncertainty about the macroeconomic variables as well as additional adjustments to monetary policy that would be appropriate to offset the effects of shocks to the economy.
If at some point in the future the confidence interval around the federal funds rate were to extend below zero, it would be truncated at zero for purposes of the fan chart shown in figure 5; zero is the bottom of the lowest target range for the federal funds rate that has been adopted by the Committee in the past. This approach to the construction of the federal funds rate fan chart would be merely a convention; it would not have any implications for possible future policy decisions regarding the use of negative interest rates to provide additional monetary policy accommodation if doing so were appropriate. In such situations, the Committee could also employ other tools, including forward guidance and asset purchases, to provide additional accommodation.
While figures 4.A through 4.C provide information on the uncertainty around the economic projections, figure 1 provides information on the range of views across FOMC participants. A comparison of figure 1 with figures 4.A through 4.C shows that the dispersion of the projections across participants is much smaller than the average forecast errors over the past 20 years.
Statement on Longer-Run Goals and Monetary Policy Strategy
Adopted effective January 24, 2012; as reaffirmed effective January 27, 2026
The Federal Open Market Committee (FOMC) is firmly committed to fulfilling its statutory mandate from Congress of promoting maximum employment, stable prices, and moderate long-term interest rates. The Committee seeks to explain its monetary policy decisions to the public as clearly as possible. Such clarity facilitates well-informed decisionmaking by households and businesses, reduces economic and financial uncertainty, increases the effectiveness of monetary policy, and enhances transparency and accountability, which are essential in a democratic society.
The Committee's monetary policy strategy is designed to promote maximum employment and stable prices across a broad range of economic conditions. Employment, inflation, and long-term interest rates fluctuate over time in response to economic and financial disturbances. Monetary policy plays an important role in stabilizing the economy in response to these disturbances. The Committee's primary means of adjusting the stance of monetary policy is through changes in the target range for the federal funds rate. The Committee is prepared to use its full range of tools to achieve its maximum employment and price stability goals, particularly if the federal funds rate is constrained by its effective lower bound.
Durably achieving maximum employment fosters broad-based economic opportunities and benefits for all Americans. The Committee views maximum employment as the highest level of employment that can be achieved on a sustained basis in a context of price stability. The maximum level of employment is not directly measurable and changes over time owing largely to nonmonetary factors that affect the structure and dynamics of the labor market. Consequently, it would not be appropriate to specify a fixed goal for employment; rather, the Committee's policy decisions must be informed by assessments of the maximum level of employment, recognizing that such assessments are necessarily uncertain and subject to revision. The Committee considers a wide range of indicators in making these assessments.
Price stability is essential for a sound and stable economy and supports the well-being of all Americans. The inflation rate over the longer run is primarily determined by monetary policy, and hence the Committee can specify a longer-run goal for inflation. The Committee reaffirms its judgment that inflation at the rate of 2 percent, as measured by the annual change in the price index for personal consumption expenditures, is most consistent over the longer run with the Federal Reserve's statutory maximum employment and price stability mandates. The Committee judges that longer-term inflation expectations that are well anchored at 2 percent foster price stability and moderate long-term interest rates and enhance the Committee's ability to promote maximum employment in the face of significant economic disturbances. The Committee is prepared to act forcefully to ensure that longer-term inflation expectations remain well anchored.
Monetary policy actions tend to influence economic activity, employment, and prices with a lag. Moreover, sustainably achieving maximum employment and price stability depends on a stable financial system. Therefore, the Committee's policy decisions reflect its longer-run goals, its medium-term outlook, and its assessments of the balance of risks, including risks to the financial system that could impede the attainment of the Committee's goals.
The Committee's employment and inflation objectives are generally complementary. However, if the Committee judges that the objectives are not complementary, it follows a balanced approach in promoting them, taking into account the extent of departures from its goals and the potentially different time horizons over which employment and inflation are projected to return to levels judged consistent with its mandate. The Committee recognizes that employment may at times run above real-time assessments of maximum employment without necessarily creating risks to price stability.
The Committee intends to review these principles and to make adjustments as appropriate at its annual organizational meeting each January, and to undertake roughly every 5 years a thorough public review of its monetary policy strategy, tools, and communication practices.